

UltraMicro Semiconductor ( AMD ) is scheduled to release its third-quarter financial report after the market closes on Tuesday, November 3rd. Prior to this, the stock tumbled 10.88% on Friday, closing at $504.80. This decline occurred after rival Intel ( INTC ) announced weak PC sales forecasts, sparking concerns across the chip sector. Wall Street expects AMD to report earnings of $1.20 per share, higher than the $1.20 from a year ago, with strong demand for AI chips and data center processors continuing to drive growth.
This chip manufacturer is entering its financial reporting period following a record-breaking second quarter. In the second quarter, the company's revenue increased by 50% year-on-year to reach $11.5 billion. Data center revenue grew by 107% to $6.7 billion, mainly driven by the increasing demand for EPYC server processors and Instinct AI accelerators. This business segment currently accounts for about 58% of AMD's total revenue.
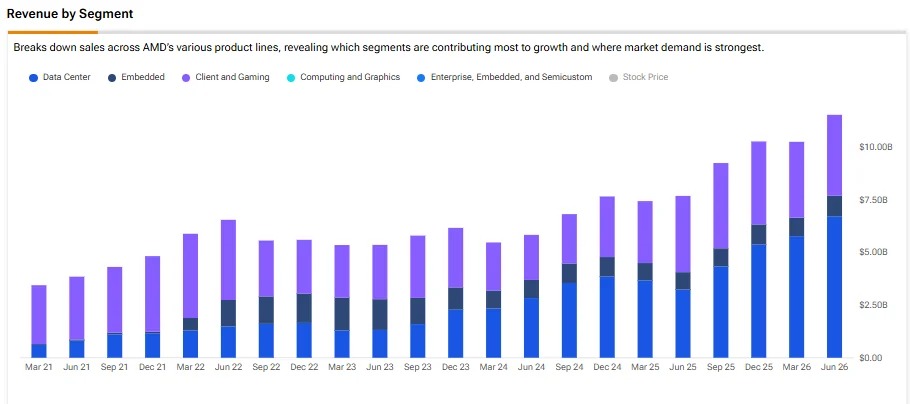
Can the AI business of AMD continue to grow?
AMD Previously, the company estimated revenue for the third quarter to be around $13 billion, with a fluctuation of $300 million, which represents a year-over-year increase of about 41%. The company also expects the adjusted gross margin to be around 56%, which is consistent with the previous quarter.
Optimism largely stems from the continuously expanding AI business of AMD. Last quarter, sales of its Instinct accelerator more than doubled, and the company also reached important AI collaborations with OpenAI, Meta ( META ), Anthropic , and Microsoft ( MSFT ).
AMD is also preparing to accelerate the shipment of its new Helios AI platform. This platform combines MI450 GPU and EPYC processors with other hardware. Initial shipments are expected to begin in the third quarter, while a more extensive growth plan is scheduled for the fourth quarter and 2027.
But the problem is that the PC business of AMD is now facing new doubts. Intel's disappointing outlook points to weaker demand for PC, higher memory costs, and tighter corporate spending. The report that AMD is about to release may show whether these pressures have also affected the sales of its Ryzen processors.
Operating costs are also a factor. AMD estimates that the adjusted expenses for the third quarter will be around $3.65 billion, as the company is investing in AI products and expanding production capacity. The company needs strong sales growth to help absorb these costs.
In addition to the quarterly data, AMD's outlook for 2027 may be particularly important. Management previously anticipated that, driven by the large-scale deployment of AI chips, data center revenues will more than double again next year.
In fact, the selling pressure on Friday has made the guidance that AMD is about to provide even more important. Its data center business is growing rapidly, but the company also sells processors to the PC market, which Intel now expects to remain weak until 2027. Whether the demand from AI can offset any slowdown in this business could affect investors' reaction to the results on Tuesday.
Is it worth buying AMD stock before the financial report?
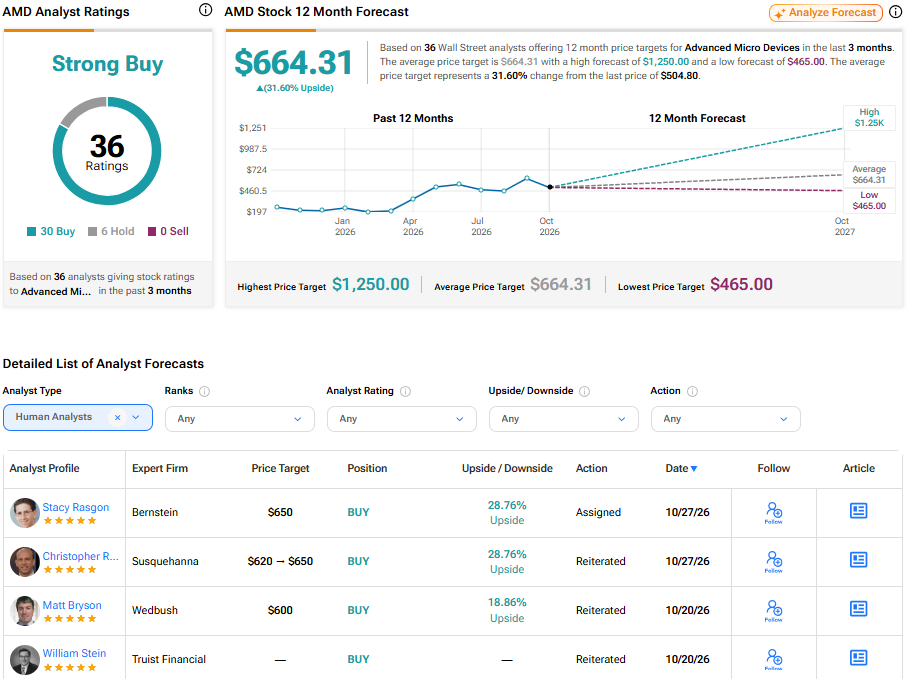
According to TipRanks data, AMD has received a unanimous "strong buy" rating from 36 analysts. Among them, 30 gave a buy rating and 6 gave a hold rating. The average target price for AMD stock is $664.31, which represents a potential increase of about 32% compared to the Friday closing price of $504.80.
Disclaimer and Disclosure Report an issue
AMD News More