

October 29 (Reuters) — Eli Lilly and Company ( Eli Lilly ) shares soared to a record high on Thursday. The sales of its weight-loss injection drugs helped the pharmaceutical company's quarterly profits exceed expectations, and it raised its full-year revenue forecast, further consolidating its leading position in the rapidly growing obesity market.
The stock price of this global healthcare company, which has the highest market value, once reached a historical high of $1,408.34 per share in the morning session, and has recently risen by 7.5% to $1,389. If this increase is maintained, Eli Lilly's market value of approximately $1.2 trillion will increase by about $80 billion.
The following are the views of some Wall Street analysts and investors:
Aptus Capital Advisors Stock Supervisor and Portfolio Manager David Wagner
Lilly has always been doing what it does best... This is the third time this year that the company has raised its performance guidance, so the performance of its core business is still ahead of expectations. The long-term strategy is on track, and the launch of oral medications ( Foundayo ) will be something worth watching.
Bahl & Gaynor Portfolio Manager Kevin Gade
"This has been a very outstanding quarter. It feels like everything that could go well for Eli Lilly did indeed go well, not only this quarter, but so far this year as well."
"Obviously, with the significant upward revision of the annual revenue forecast, the company's performance in the fourth quarter is expected to be very strong."
JPMorgan analyst Chris Schott
Lilly remains our preferred target, and there is still room for its performance to exceed market expectations in the coming years (especially in markets outside of the United States).
Schott indicates that a series of catalytic factors in the future are expected to expand the company's leading position in the obesity and diabetes market, which is worth over $200 billion.
BMO Capital Markets Analyst Evan Seigerman
The significant underperformance of “Foundayo” may raise doubts about the effectiveness of the company's current pricing strategy and measures to expand accessibility... Despite the price erosion faced by the entire (“GLP-1”) product portfolio, sales volumes have continued to largely offset these unfavorable factors.
Gabelli Funds Portfolio Manager Daniel Barasa
"Considering the strong cash position brought about by the explosive growth of GLP-1 drugs, and the significant increase in trading activities, this is a way to reasonably diversify the company's business."
Pricing outside of medical insurance ( Medicare ) seems to remain resilient, and recent prescription trends may partially reflect seasonal factors.
Guggenheim Securities Analyst Seamus Fernandez
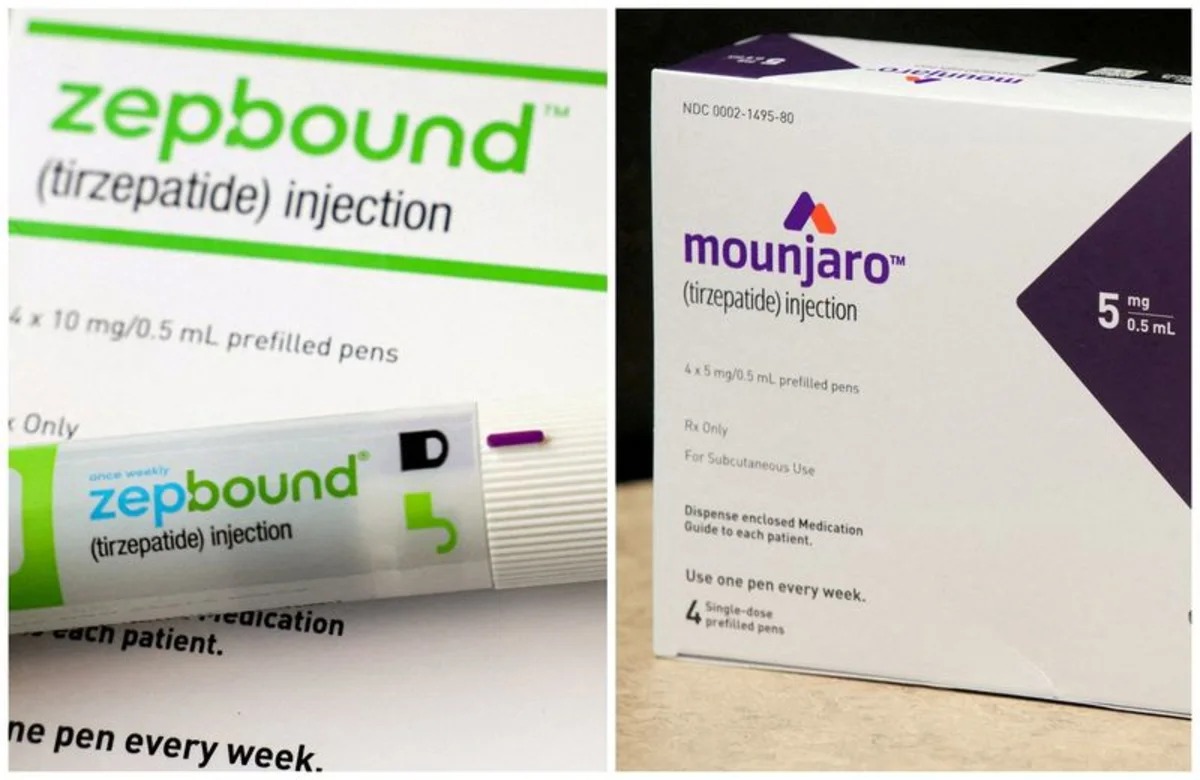
The cardiovascular and metabolic business continued to perform exceptionally well, with diabetes medications Mounjaro and Jardiance significantly exceeding expectations.
He also added that the company's Alzheimer's disease drug Kisunla is slowly moving towards the status of a blockbuster drug.
The company's sales in the third quarter Kisunla amounted to 193 million US dollars, which is higher than the analysts' estimate of 175.2 million US dollars.
(Reported by Sriparna Roy and Christy Santhosh from Bangalore; Edited by Bill Berkrot)