IT News on October 7th: Market research firm CounterPoint Research published a blog post today (October 7th) stating that in the second quarter of 2026, total smartphone sales in Europe decreased by 8% year-on-year, with sales through operator channels declining by only 4% year-on-year, while smartphone sales in the free market fell by 11%.
The institution believes that operator channels are less affected by rising memory costs due to the high proportion of contract phones and the concentration of high-end models; in addition, high-end brands have stronger sales resilience in operator channels.
In terms of brand landscape, in terms of market share, Apple and Samsung still hold a dominant position. In the second quarter of 2026, Apple surpassed Samsung's 34% share with 37%, becoming the number one brand in terms of market share among European operators. IT Here are the relevant images attached:
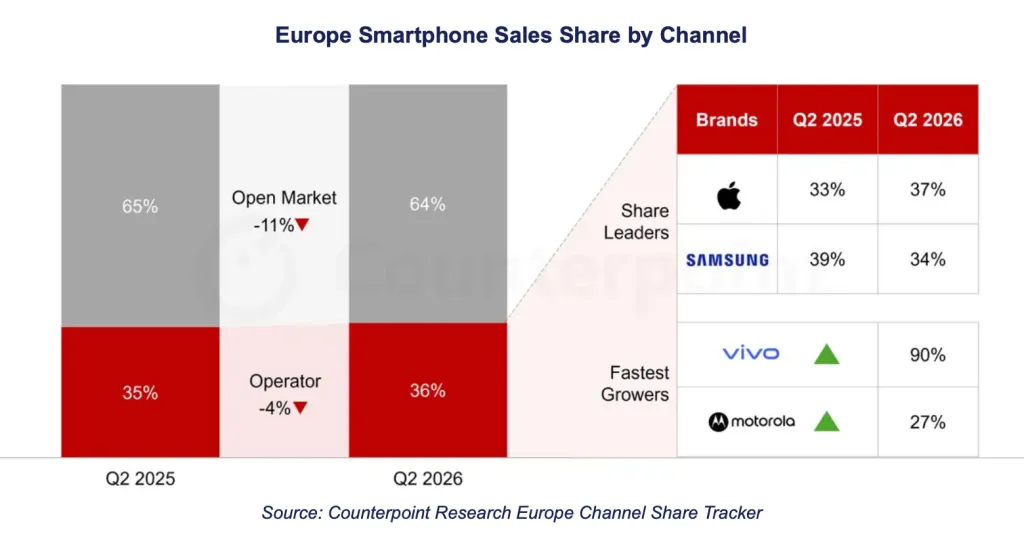
In terms of growth, vivo saw a year-on-year increase in sales through operator channels by 90%, becoming the brand with the fastest growth rate. Motorola ranked second with a growth rate of 27%. In the same period of 2025, Google and Honor were the leaders in growth rate, marking a clear shift in the brand landscape.
Memory prices continue to rise, leading to a significant increase in the cost of low-end smartphones. The European low-end market has been hit the hardest, with a noticeable decline in sales volumes in the free market. Since users tend to opt for contract-based phone purchases, operators are less sensitive to price changes.
Counterpoint Research Deputy Director Jan Stryjak indicated that the operator channel share may continue to grow in the coming quarters. The low-end market is still affected by the memory crisis, and the recovery speed of the free market is relatively slow.
refer to
European Operator Channel Benefits from Low-end Collapse in Region ’s Smartphone Market in 2026