

Stocks can be converted into on-chain tokens, but dividends do not automatically find their holders as a result. On October 1st, Chainlink announced its plan to participate in the 2026 Swift Hackathon Business Challenge: utilizing Chainlink Runtime Environment ( CRE ) to coordinate the tokenization of stock cash dividends. The process, from company action notifications and equity snapshots to cross-blockchain payments and final reconciliation, requires no manual intervention at each step. This plan won the runner-up award in the challenge. It is a demonstration for a specific scenario and does not represent that the real securities market has already used it on a large scale for dividend distribution.
This distinction is very important. In daily stock dividends, there are registration institutions, payment agents, and relatively centralized lists of holders. However, when the same type of tokenized shares are distributed across multiple public chains and permissioned chains, it becomes complicated to determine who holds how much on the registration date and how to count these shares during cross-chain transfers. Distributing the dividend payments is just the final step; before that, it is necessary to ensure that no one receives dividends twice for the same holdings on two different chains, and that no one is overlooked due to timing differences in network confirmation.
The difficulty is not in fast transfers, but in accurately determining "who has the right to receive the money".
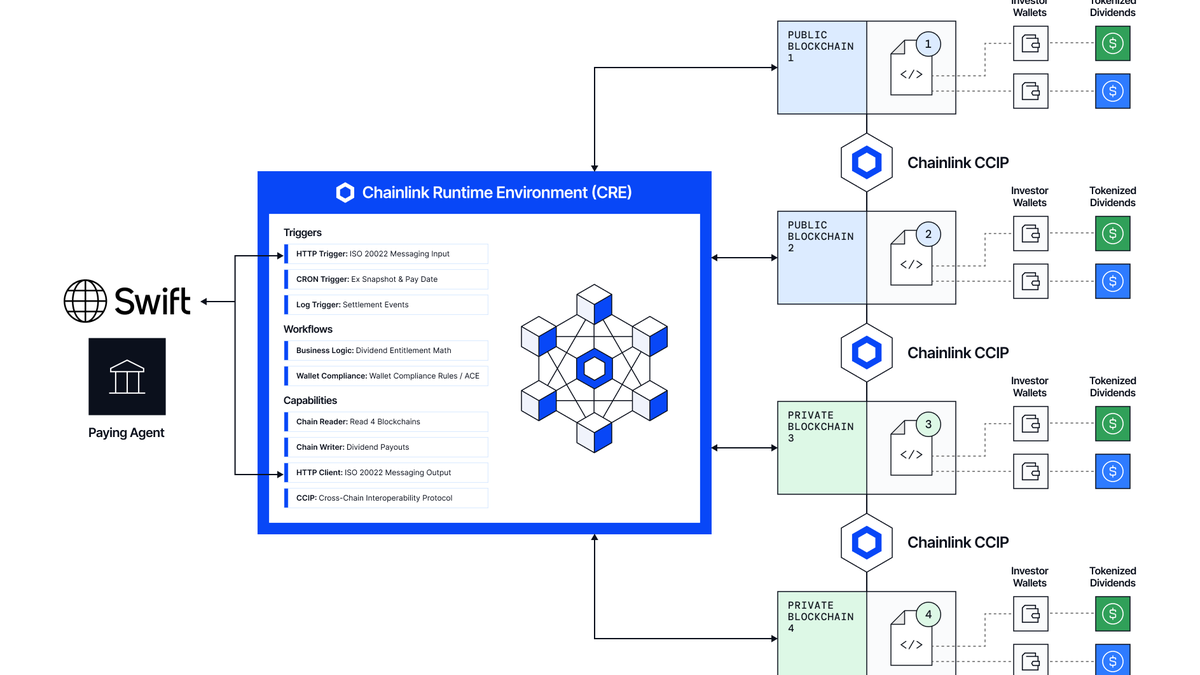
Chainlink Introduction: The process starts with receiving notifications of company actions from ISO in 2022, arranging for equity snapshots and payment dates, reading the holdings on each chain, and then merging them into a single registration result that can be used to calculate dividends. Different chains have different requirements for transaction confirmation and finality, and there may be intervals where tokens are locked on the source chain but not yet confirmed on the target chain during cross-chain transfers. The demonstration solution specifically defines the ownership of such holdings before and after the cut-off time to avoid double counting or completely missing any transactions. For capital markets, this aspect is even more decisive than the seemingly instant transfer times.
The scheme also incorporates identity verification, sanction lists, tax status checks, and investor qualification assessments into the process. It utilizes the Chainlink compliance components to filter eligible wallets before dividend calculations; if price adjustments are required, the corresponding data sources are called upon. Compliance rules are not about assigning a permanent "good guy" label to addresses on the chain: investors' identities and regional qualifications can change, and different assets may have different restrictions. Payment agents must ultimately retain responsibility for the calculation basis, exception handling, and regulatory reporting. They cannot shift legal responsibilities to software just because CRE automatically orchestrates these actions.
On the payment side, different holders are allowed to receive stablecoins or tokenized deposits on their respective chains. If the target chain does not have native settlement assets, the scheme uses CCIP for transmission. Each payment is linked back to the original company's action messages, creating a traceable audit trail. Even failed payments can be identified and retried. The statement "no manual intervention required" is an official description of the end-to-end process in the challenge competition and should not be interpreted as meaning that all exceptions, disputes, tax issues, and recovery procedures in the real market will no longer require human intervention from now on.
Traditional ISO 20022 messages are based on calendar dates and fiat account payments, and do not naturally include fields such as cross-blockchain precise snapshot moments, recipient wallets, target chains, and settlement tokens. Chainlink Therefore, an extension of information for company actions and payment messages has been proposed to record references to on-chain transactions. This is a "proposed extension" that has not yet been officially adopted as a standard by ISO, nor has it been uniformly deployed by financial institutions. For technical solutions to be put into practice, standard governance, legal interpretations across jurisdictions, and interoperability of infrastructure are all required to keep up.
After securing the runner-up position, there are still several hurdles to overcome before receiving the actual securities dividends.
Official materials clearly state that the participating solutions deal with single cash dividend events. Although the principles can be extended to company actions such as interest payments, redemptions, stock splits, and rights issues, such expansions still fall within the realm of possibilities rather than being part of a list of already implemented products. Especially when equity is transferred between multiple chains, the registration institutions must be able to prove that no snapshots are missed or duplicated, the payment agents must be able to demonstrate that funds ultimately arrive at their destinations, and the issuers must also be able to explain which chain records are valid under local laws. These are not matters that can be decided by a hackathon demonstration for the market.
In a real-world environment, one also has to deal with issues such as chain pauses, bridge failures, accidental payments, and the need to update identity information. If a transaction on a certain chain cannot be confirmed for a long time, should all payments be postponed, or should other chains be paid first? When the settlement asset price becomes unstable, should dividend obligations be calculated based on the amount in US dollars or the number of tokens? If a wallet is restricted from trading after the registration date, how should the funds be preserved and how can one file a complaint? Being able to explain these exceptional situations is key to moving from "technically automatable" processes to a situation where "institutions can take responsibility." The materials provided by Chainlink show the orchestration paths, but there are no unified answers yet to these institutional issues.
This demonstration is not the same news event as CCIP 2.0 previously launched by Chainlink. CCIP represents a layer of cross-chain transfer capability, while this competition entry plan integrates company action notifications, position snapshots, compliance checks, and payments into a specific workflow. Simply referring to it as “Chainlink cross-chain upgrade” may overlook new issues and could easily lead to duplication with past reports. What is more valuable for readers to understand is that once shares can be transferred across chains, the shareholder registers and dividend distribution processes, which are currently maintained centrally, also need to be updated accordingly.
The next step worth observing is not whether "blockchain can transfer a sum of money," but whether there are issuers, registries, and payment agents conducting pilots in a regulated environment, and whether they make the snapshot rules, fault handling procedures, and audit results public. What is currently certain is that the demonstration on four chains has been completed, and they have won the runner-up in the challenge competition; however, large-scale deployment, standard adoption, and regulatory recognition cannot be announced yet. For cross-chain assets to become a true infrastructure for the securities market, one fundamental question still needs to be answered: whether every person entitled to receive dividends can receive their money on time, in full, and in a traceable manner.