

Seagate Technology ( NASDAQ : STX ) and Western Digital ( NASDAQ : WDC ) suffered heavy losses on Friday, with both stocks falling by about 13% during the session. The selling pressure stemmed from reports that Toshiba plans to double its hard drive production capacity by the fiscal year 2027, which raised concerns in the market that one of the biggest advantages that Seagate and Western Digital have long enjoyed – the tight supply in the industry – may eventually begin to weaken. Toshiba plans to invest about 60 billion yen (approximately $380 million) in this expansion and hopes to increase its HDD production share from just over 10% to around 30% in the medium term.
After a significant increase in the prices of these two stocks earlier on, this prospect is particularly concerning. The AI data centers have created a strong demand for large-capacity storage, and the limited supply has helped hard drive manufacturers to raise prices and improve their profitability. More production capacity from Toshiba may eventually challenge this favorable balance, but such expansion will take time, and analysts also question how much change the competitive landscape will actually undergo.
Goldman Sachs is more optimistic about Seagate
In this context, Goldman Sachs analyst James Schneider believes that holding Seagate is a strong reason. Schneider ranks in the top 3% of Wall Street analysts.
Schneider believes that driven by strong margin profits and the promotion of thermal assisted magnetic recording (HAMR) technology, Seagate is expected to achieve significantly higher profit growth than its peers in the coming year. Higher profits may also allow the company to have more room to return capital to shareholders while repaying the remaining debt.
This analyst stated, "Considering the recent pullback, we will buy this stock." He believes that Seagate should continue to benefit from the tight industry supply and strong pricing, and will still be a key winner.
Schneider gives Seagate a buy rating with a target price of $960, which means there is approximately 17% room for growth for STX.
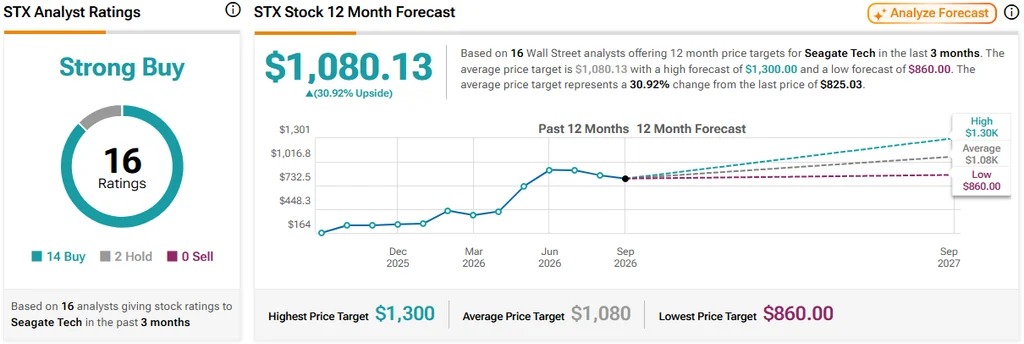
Western Data has more upward room, but its rating is only for holding.
Interestingly, the figures provided by Schneider indicate that Western Data has much more room for growth, yet his rating is not so optimistic.
This analyst expects that as the proportion of cloud customers in industry demand continues to rise, Western Digital will benefit from it, and it will also be advantageous for hard drive manufacturers to maintain a disciplined supply. However, when making a choice between the two stocks, Schneider still favors Seagate more.
This also explains why, despite Schneider setting a target price of $615, implying a potential increase of about 52%, Goldman Sachs still only assigned a rating to Western Data.
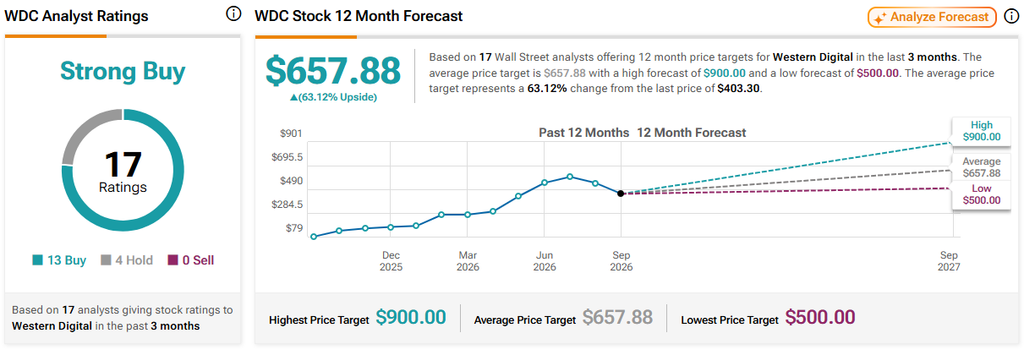
However, other analysts on Wall Street are more optimistic about Western Data than Schneider's holding rating. The current consensus rating for WDC is a strong buy, with 13 out of 17 analysts recommending a buy and 4 giving a hold rating. An average target price of $657.88 implies a potential increase of about 63% from the current level. (See WDC stock price forecast)
Disclaimer and Disclosure Report an issue
Seagate Technology News More