CBN News, October 3, 2026, 07:18:05 - Listen to the news
Author: Chu Chu
Editor-in-Chief: Pan YinruOn October 2nd local time, the three major U.S. stock indices all closed higher.
U.S. non-farm employment growth in September fell significantly below expectations, leading the market to further reduce bets that the Federal Reserve would continue to raise interest rates this month, with tech stocks leading the market gains. Within the semiconductor sector, there was a divergence in trends; optical communication stocks continued to perform strongly, while Seagate Technology and Western Digital both fell by more than 10%.
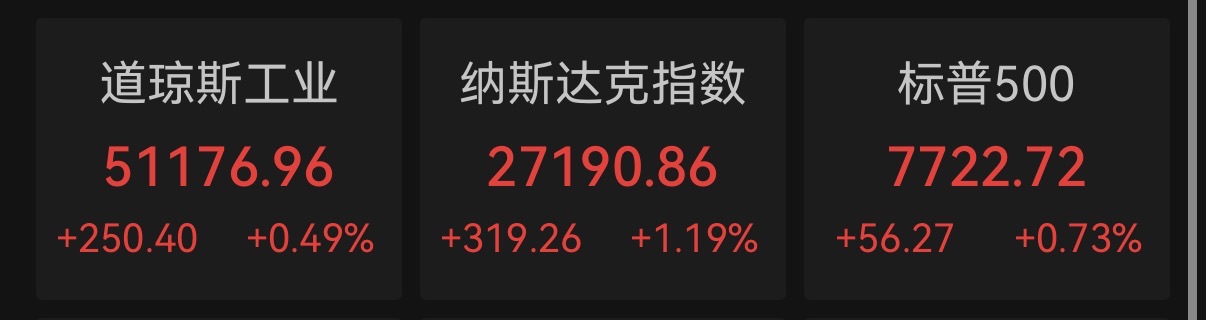
As of the close, the Dow Jones Industrial Average rose by 250.40 points, or 0.49%, to 51,176.96; the Nasdaq Composite Index rose by 319.26 points, or 1.19%, to 27,190.86; and the S&P 500 Index rose by 56.27 points, or 0.73%, to 7,722.72.
On a weekly basis, the Dow Jones Industrial Average fell by 1.26%, the S&P 500 Index declined by 0.27%, while the Nasdaq Composite Index rose by 0.45%.
Market Overview
The cooling of the U.S. labor market became the main focus of trading on that day. The U.S. Department of Labor announced that non-farm employment increased by 29,000 people in September, lower than the 90,000 expected by economists surveyed by Reuters. The unemployment rate rose slightly from 4.1% in August to 4.2%, and the labor force participation rate was 61.8%.
Employment data for the previous two months was also revised downward. In July, non-farm employment was revised from an increase of 21,000 people to a decrease of 10,000 people, and in August, it was revised from an increase of 162,000 people to an increase of 133,000 people, resulting in a total revision of 60,000 people. After the revisions, the average monthly increase in employment over the past three months is about 51,000 people.
Salary increases were also modest. In September, the average hourly wage in the private sector rose by 0.1% month-on-month to $37.81, and by 3.0% year-on-year; the average weekly working hours remained at 34.4 hours. By industry, healthcare added 17,000 new jobs, which is lower than the average monthly increase of 33,000 jobs over the previous 12 months; construction and manufacturing each added 11,000 and 9,000 new jobs, while financial activities saw a reduction of 7,000 jobs.
The employment report further weakened the expectations for an interest rate hike in the near term. According to data from CME FedWatch, the market's probability of a 25-basis-point interest rate hike at the Fed's October meeting is now 22.7%, down from 24.4% on the previous trading day and 64.2% a week ago.
SummitTX Capital Trading Director Robert Burnstone stated that the data has alleviated concerns about economic overheating and short-term interest rate hikes, but investors still need to pay attention to economic growth and inflation risks. The market remains cautiously optimistic overall.
Fed officials remain cautious in their statements. On that day, Chicago Fed Chairman Charles Plosser stated that the latest employment data reflects overall stability in the labor market, while high inflation remains a more concerning issue. Regarding whether to raise interest rates this month or pause, he believes both options should be kept open, and more evidence is needed to confirm that inflation is returning towards the 2% target.
The bond market failed to maintain the gains seen after the release of the employment report. U.S. Treasury yields fell in the early session before rebounding later on. Data from the U.S. Treasury Department showed that the yield for 2-year bonds was at 4.83%, up 5 basis points from the previous trading day; 10-year bonds yielded 5.28%, up 4 basis points; and 30-year bonds yielded 5.63%, up 2 basis points.
Regarding the situation in the Middle East, according to CCTV News, on the 2nd local time, the UK Maritime Trade Operations Office reported that an oil tanker departing from the Strait of Hormuz was hit by an unidentified projectile, resulting in a fire on board and a temporary power outage. The fire was subsequently brought under control, and the vessel continued its voyage. No reports of casualties or environmental pollution have been received yet, and the relevant authorities are investigating the incident.
According to CCTV news, on the evening of the 2nd, the Houthi armed forces in Yemen issued a statement claiming that their controlled areas were subjected to 94 airstrikes by Saudi Arabia over the past 24 hours, affecting multiple provinces including Sanaa, Sada, and Taiz, resulting in casualties.
Popular Stocks Performance
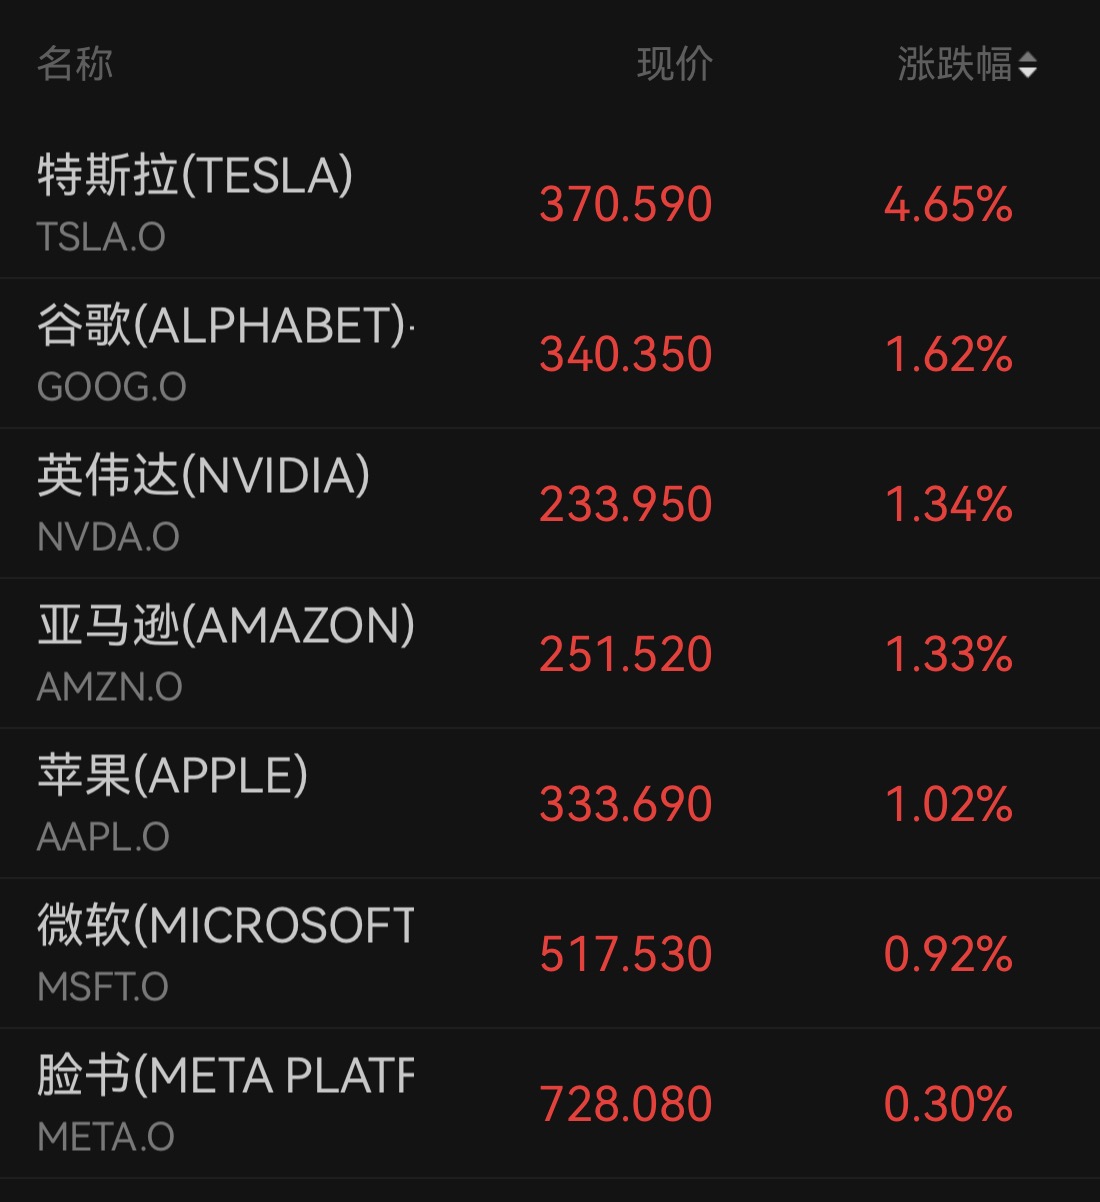
Large tech stocks all rose. Tesla gained 4.65%, Google rose 1.62%, NVIDIA rose 1.34%, Amazon rose 1.33%, Apple rose 1.02%, Microsoft rose 0.92%, and Meta rose 0.30%.
Tesla's third-quarter delivery numbers exceeded market expectations. The company delivered 486,532 vehicles during that quarter, produced 464,391 vehicles, and deployed 13.7 gigawatt-hours of energy storage products. The company plans to release its third-quarter financial report after the U.S. stock market closes on October 21st.
The Philadelphia Semiconductor Index rose by 2.40%. Broadcom increased by 3.35%, TSMC ADR rose by 2.96%, AMD rose by 2.95%, Marvell Technologies rose by 1.57%; Intel fell by 0.56%.
Optical communication stocks strengthened, Coherent rose by 5.59%, Lumentum rose by 3.79%.
Storage sectors faced a sell-off. Western Digital fell by 10.22%, Seagate Technologies fell by 10.21%, Sandisk fell by 3.79%, and Micron Technology fell by 2.05%. Meanwhile, Toshiba plans to invest approximately $380 million to expand its factory in the Philippines, doubling its hard drive production capacity. The news of the expansion has sparked concerns about intensified competition, putting pressure on the stock prices of hard drive manufacturers.
Nike falls 3.64%. The company's revenue in the first fiscal quarter was $11.2 billion, a year-on-year decrease of 4%; revenue in Greater China region decreased by 26% when calculated using a fixed exchange rate. Nike expects its revenue to decline by more than one digit in the fiscal year 2027 and has announced plans to advance business adjustments and cost-cutting measures.
After a sharp rise on the previous trading day, Accenture fell back, closing down 6.31%.
Most popular Chinese concept stocks fell, with the NASDAQ China Golden Dragon Index dropping 2.09% to 5,519.24 points. Li Auto fell 3.87%, NetEase fell 2.82%, Bilibili fell 2.30%, JD.com fell 2.24%, Xpeng Motors fell 1.80%, Ctrip fell 1.73%, Alibaba fell 1.49%, Baidu fell 1.48%, Pinduoduo fell 1.46%, and NIO fell 0.88%.
Large-cap performance
International oil prices closed lower in both cases. The settlement price of November crude oil futures fell by $1.76, a decrease of 1.90%, to $91.11 per barrel; the settlement price of December Brent crude oil futures fell by $0.06, a decrease of 0.06%, to $102.25 per barrel. Both contracts saw larger declines at one point during the session, but then the declines narrowed later on, with Brent oil still remaining above $100 per barrel.
Energy supply policy has become another focus of market attention. According to CCTV News, the leaders of the G7 held a video conference on the 2nd, agreeing to increase diesel production by adjusting refinery maintenance plans and raising equipment operation rates, and to assist in releasing 100 million barrels of reserve oil into the market through the International Energy Agency (IEA). The release plan is to be completed within four months, with a focus on releasing diesel in the first 20 days. Member countries also pledged not to impose energy export restrictions on each other.
Precious metals are declining. The settlement price of December gold futures fell by $40, a decrease of 0.95%, to $4,162.30 per ounce; December silver futures fell by $0.760, a decrease of 1.24%, to $60.415 per ounce. The employment report once boosted gold prices, but as U.S. Treasury yields rebounded, gold failed to maintain its intraday gains.
Article Author