The scale of shutdowns at refineries around the world has surpassed even the worst-case scenarios predicted by Goldman Sachs, and the tight supply of refined products is expected to continue until 2027. Crude oil prices may be depressed by diplomatic headlines, but the damaged refineries cannot restart through negotiations.
According to the latest report released by Goldman Sachs' Commodity Team on October 25th, "Oil Product Tracking: Weak Supply May Continue Until 2027," the scale of production cuts at refineries in the Middle East is about 1.6 million barrels per day higher than the seasonal normal level, while Russian refineries are cutting production by about 4.2 million barrels per day. Together, these excess production cuts amount to approximately 5.8 million barrels per day, which has surpassed the worst-case scenario of 5 million barrels per day estimated by Goldman Sachs analyst Nikhil Bhandari in their September report on the "catastrophic refining crisis." At the same time, this autumn's refining plant maintenance season is unusually quiet, with a large number of postponed maintenance tasks expected to be carried out in the second quarter of 2027. By then, the planned production cuts in Asia (excluding China)—especially in India and South Korea—will far exceed the seasonal normal level.
A Goldman Sachs report indicates that the global average retail fuel price is around $223 per barrel, and inventories of refined oil are at low levels at major hubs, with little buffer space to absorb additional supply shocks. Although both European oil demand and US gasoline demand have declined by about 2% year-on-year, reflecting a weakening on the demand side, inventories continue to fall. The logic of war on the supply side has overwhelmed the textbook-based demand response. Against this backdrop, Goldman Sachs reiterates its bullish stance on European summer gasoline in 2027, positioning it as a tool to hedge against further geopolitical escalation.
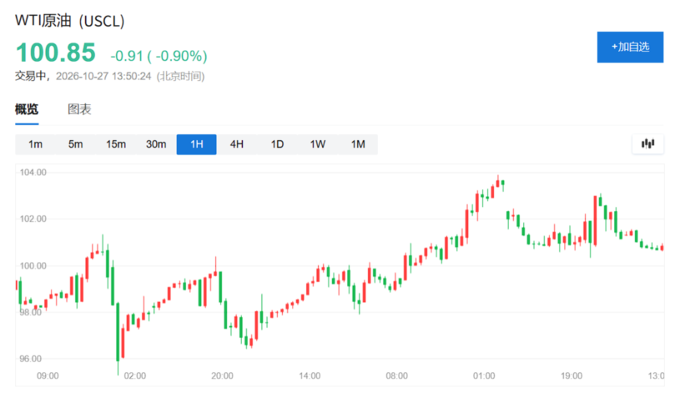
On Monday, Brent crude oil tumbled 1.4%, and WTI fell 2%. The market was trading on expectations of a deterioration in relations between Washington and Tehran. However, Goldman Sachs' commodities team believes that the real story has shifted to the downstream sector – the war premium has never left this oil; it has merely shifted from crude oil to refineries, oil tanker leases, and gas stations. Francisco Blanch, the head of commodities at Bank of America, stated that if Iran attacks regional infrastructure again, it is "very likely" that oil prices could reach $120 per barrel in the coming months.
Freight costs soar: from $3 to $24, refined oil transportation capacity under dual pressure
In October, Goldman Sachs' global average crude oil freight rate reached a historic high of $24 per barrel, compared to around $3 a year ago.
Rising freight costs have had a dual impact: firstly, the net profit margins of refineries that rely on long-distance crude oil imports (mainly located in Asia and Europe) have been squeezed; secondly, some refined oil tankers have been repurposed for crude oil transportation, directly reducing the maritime capacity for transporting refined oil.
The report indicates that the logical chain is clear: when transporting crude oil is more profitable, clean tankers switch to carrying crude oil, resulting in gasoline, diesel, and aviation fuel that should have been transported by these vessels remaining at the refineries. High freight costs cause a single blow to crude oil buyers, while for fuel buyers, it results in a double blow.
Structural divide in Persian Gulf exports: Crude oil exports have recovered, but refined products are still far behind
Crude oil exports from the Persian Gulf have approached the average level for 2025, but there is still a significant gap in refined oil exports, which continues to support prices.
According to data cited by Goldman Sachs from Kpler, the latest crude oil exports from the Persian Gulf are about 153,000 barrels per day, which is 92% of the level expected in 2025; meanwhile, aviation fuel exports are only 54% of the 2025 level, diesel/gas oil exports are at 34%, and gasoline exports are even lower at 10%.
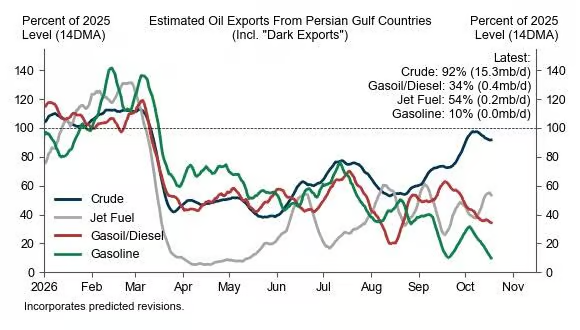
The fundamental reason for this differentiation lies in the fact that the ship-to-ship transfer scheme that supports crude oil transportation is difficult to replicate in the refined oil sector. A Goldman Sachs report points out that the higher flammability and varying specifications of refined oil make transfer operations outside the Persian Gulf more complex.
In addition, large crude oil tankers can spread the fixed safety costs (including compensation for crew war risks) over a larger number of barrels, whereas refined oil tankers do not have this advantage. In other words, the alternative solutions for the Strait of Hormuz are designed for crude oil, not for aviation fuel.
5.8 million barrels per day: Goldman Sachs' worst-case scenario has been shattered by reality
These are the most crucial figures in this report.
Goldman Sachs analyst Nikhil Bhandari set a "prolonged disruption scenario" in their September report: assuming that the shutdowns of refineries in the Middle East and Russia continue to exceed the seasonal normal level by 5 million barrels per day for the remainder of 2026 and throughout 2027, while demand growth is only 500,000 barrels per day. This is already the worst-case scenario they have outlined.
However, according to the latest data from Goldman Sachs, Middle East production cuts exceed 1.6 million barrels per day, while Russia's production cuts exceed 4.2 million barrels per day. Together, these amount to about 5.8 million barrels per day, which has already surpassed Goldman Sachs' own worst-case assumption of 5 million barrels per day.
There are no signs of improvement on the Russian side: Ukraine continues to attack Russian refineries after Trump announced a "cease-fire on energy," while Washington is currently importing Russian diesel under the framework of the Trump-Moscow fuel agreement. Meanwhile, the only large refining system with spare capacity—the United States—no longer has any surplus.
According to data from the U.S. Energy Information Administration ( EIA ), the operating rate of refineries in the United States has just reached its highest level since 1998. Operating at full capacity is beneficial for profit margins, but it also means that the next long-term shutdown for maintenance is not far off.
Maintenance bills will mature in bulk during the second quarter of 2027.
A postponed maintenance task is not a cancelled one; it is more like a loan.
Goldman Sachs data shows that the planned global maintenance volume this autumn has decreased by 1.7 million barrels per day year-on-year, a reduction of 27%, mainly driven by the postponement of maintenance activities in the United States. These postponed tasks will be carried out intensively in the second quarter of 2027, when the planned production cuts are expected to increase significantly. The region with the most notable increase is Asia (excluding China), with India and South Korea being the most affected.
According to Goldman Sachs' charts, the planned maintenance peak in 2027 is approximately 7.7 million barrels per day (around May), which is higher than this year's peak of about 6 million barrels per day; in Asia (excluding China), the planned production cuts in the second quarter of 2027 will exceed the seasonal normal level by 140%. Given the important role of India and South Korea in global refined oil exports, Goldman Sachs warns that this will significantly reduce the export supply of diesel and aviation fuel in the second quarter of 2027.
Goldman Sachs also specifically pointed out that delaying maintenance will increase the risk of unplanned production stops and further tighten the supply of refined oil – this is akin to a car running at top speed without undergoing maintenance. The United States has already skipped this maintenance this autumn, while India and South Korea will be next next spring. Meanwhile, the already damaged refineries in the Middle East and Russia still need to be repaired.
There is no inventory buffer, and the current demand disruption is not sufficient to reverse the situation.
Even though demand is on the decline, inventory continues to be depleted.
Goldman Sachs pointed out that inventories of high-frequency refined products at major hubs remain low, with little capacity to absorb additional supply shocks: gasoline and diesel inventories in the United States are still below historical ranges; gasoline and diesel inventories in China have decreased by 8% and 11% year-on-year, respectively; intermediate distillate oil inventories in Singapore have decreased by 44% year-on-year; aviation fuel inventories at the Amsterdam-Rotterdam-Antwerp (ARA) hub have decreased by 56% year-on-year, as local refineries continue to prioritize the production of diesel.
The pressure on the demand side indeed exists. According to Goldman Sachs data, the global average retail fuel price is around $223 per barrel, with both European oil demand and US gasoline demand declining by about 2% year-on-year, and aviation fuel demand is also weak. However, the problem is that despite the measures taken to address demand, inventories continue to fall—structural damage on the supply side has overwhelmed the automatic adjustment mechanisms on the demand side.
At the crack spread level, according to Bloomberg data, the Nymex gasoline crack spread fell to $27.94 per barrel on Friday, the lowest level since April; whereas the heating oil (diesel) crack spread was as high as $98.45 per barrel, about 3.5 times that of gasoline crack spread. The December-December spread for the Brent crude oil curve reached $29.98 per barrel, marking the strongest futures premium on a rolling basis, indicating that the market does not believe in the narrative of demand panic.
Goldman Sachs trading advice: Go long on European gasoline in the summer of 2027
Goldman Sachs first recommended a long position in European gasoline for June 2027 in mid-September, and reiterated this stance in a report on October 25.
Goldman Sachs stated in the report: "In the face of high uncertainty regarding the supply prospects from the Middle East and Russia, we reiterate our bullish recommendation for European summer gasoline in 2027 to hedge against the risk of further escalation in geopolitics."
The report states that the logical chain is clear: The summer of 2027 coincides with the time window for Asia to postpone maintenance and centralized settlement, which also marks the beginning of the peak driving season. It is also the period when refineries that have barely managed to get through this winter by skipping maintenance are most likely to experience failures. Gasoline is currently the relatively “cheap” component among refined products—the crack spread for gasoline in the United States is at its lowest level since April—therefore, it represents the lowest-cost way to hold onto positions with tight refined product supply.
It is worth noting that Goldman Sachs categorized it as "hedge" rather than "forecast," which is a choice of wording to express directional judgment without the need for precise timing.
Goldman Sachs also maintains a bearish stance on crude oil: it is expected that Brent crude will fall to $90 per barrel in December and average $80 per barrel in 2027. Being bearish on crude oil and bullish on refined products is in itself the clearest signal: the war premium can be negotiated down from crude oil prices, but it cannot be negotiated back to normal levels from damaged refineries.