The cracks in the infrastructure financing model of AI are accelerating in size.
Under the dual pressures of unexpectedly strong inflation data and rising U.S. Treasury yields, the stock price of data center operator CoreWeave tumbled by more than 15% on Wednesday, recording the third-largest one-day decline in history, and was just a step away from its historical low.
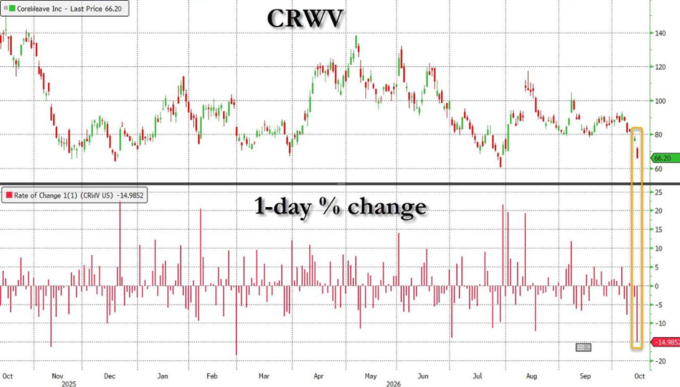
At the same time, the yield on the company's bonds maturing in 2032 exceeded 15%, officially pushing it into a difficult situation. This sharp decline caused the market value of several AI infrastructure stocks, including CoreWeave, to evaporate by approximately $80 billion in a single day.
D.A. Analyst Gil Luria issued a warning in a podcast, stating that if CoreWeave is unable to repay its high-cost debts, the company's "equity value will be zeroed out."
According to Bloomberg, CoreWeave CEO Mike Intrator immediately issued an internal memo, characterizing the sharp drop in stock prices as "irrational" market behavior. He also expressed confidence in the company's business model, financial condition, and backlogged orders, stating that the scale of the backlogged orders is sufficient to cover all debt repayment obligations.
This sell-off is not an isolated incident. The continuous rise in U.S. inflation data pushed the yield on 30-year U.S. Treasury bonds to 5.63% at one point, suddenly highlighting the financing cost risks for capital-intensive AI enterprises.
Oracle fell by about 9% in a single day, Dell Technologies dropped by over 11%, AI infrastructure provider Nebius saw a decline of 10%, and the Nasdaq 100 index as a whole tumbled 2%.
The alarm in the bond market came weeks before that in the stock market.
The signs of pressure in the bond market appeared several weeks ago, but the stock market only reacted this week.
According to LSEG data, CoreWeave has issued approximately $22 billion in bonds and $26 billion in loans. The bonds issued in June of this year had a coupon rate of 9.625%, and the latest yield has risen to around 15%, a level that is typically seen in junk bonds rated CCC or lower.
The price of this bond has fallen below 80 cents, officially entering the “deep distress” range defined by the market, and its yield spread over government bonds has also crossed the default warning threshold of 1000 basis points.
Wall Street Journal mentioned that this AI cloud service provider, supported by NVIDIA, has raised over $35 billion this year through channels such as chip mortgage loans, high-yield bonds, convertible bonds, and stock offerings.
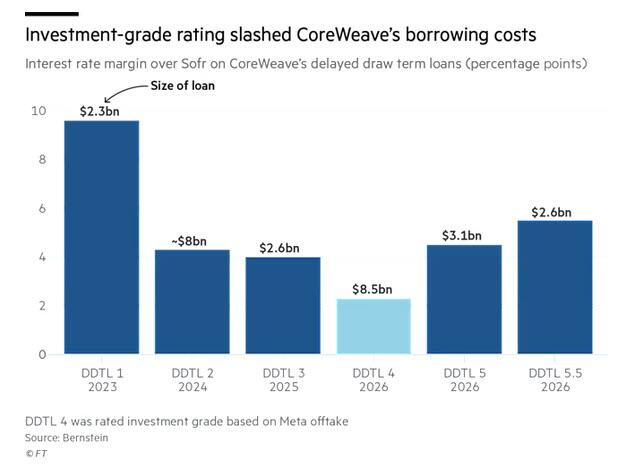
Its co-founder Brannin McBee stated that once more chip-backed debts receive investment-grade ratings, CoreWeave will be able to gain access to the funds of insurance companies, where the capital is “infinite; it’s all the money in the world.”
Analyst Jordan Chalfin told the UK's Financial Times that CoreWeave is "highly creative" in terms of financing, but investors are deeply concerned about the mismatch between its long-term data center leases and relatively short customer contracts.
He asked,
If there is an oversupply, why would customers want to renew their contracts with CoreWeave?
Even Elon Musk responded to the pressure on CoreWeave bonds on social media, stating that "the demand for supercomputing data centers is indeed high, but raising funds to build them involves complex hardware systems for large-scale power, cooling, and networking, which is completely different from the actual implementation."
Analyst: Borrowing costs far exceed investment returns, and equity value faces the risk of zeroing out
The core logic of Luria directly points to the fundamental flaw in the business model of CoreWeave: The company borrows at an interest rate of about 9%, yet its return on investment is only around 1%. Even if calculated according to the company's own target of 4% to 5%, it is still lower than the financing cost.
He compared this to borrowing at a 9% interest rate to buy U.S. Treasury bonds that yield only 5%, which is a strategy of value destruction.
Financial data confirms this judgment. In the second quarter, CoreWeave incurred net interest expenses of $640 million, doubling from the same period last year ($267 million), and had a net loss of $626 million during the same period. Interest expenses accounted for approximately 25% of the current period's revenue.
As of the end of June this year, the total debt and leasing obligations of CoreWeave amounted to approximately $52 billion. According to the consensus forecast of Visible Alpha, between 2026 and 2028, the company is expected to have a cumulative negative free cash flow of $71 billion, with an estimated negative cash flow of about $25 billion this year and about $28 billion next year.
In the face of external doubts, CoreWeave, co-founder with Brannin McBee, told The Financial Times that he "completely does not consider these debts to be a cause for concern," stating that borrowing was done to accelerate expansion.
He also stated that the company is expected to achieve an investment-grade credit rating within "a few years," and added, "If we stop building today, (the company) will immediately enter a highly positive cash flow situation."
However, according to S& P Capital IQ data, the three co-founders of CoreWeave have cashed in approximately $2 billion by selling stocks this year. McBee describes this as a diversification of personal wealth and emphasizes that most of their wealth remains in the company's stocks.
On the prediction market platform Polymarket, traders currently estimate that there is a 17% chance that CoreWeave will declare bankruptcy by December 2027, and this probability rises to 27% by 2029.
Interest rate upside pressure spreads to the AI industry chain
The predicament of CoreWeave reflects broader market concerns: in an environment where interest rates remain high, the financing logic of capital-intensive AI infrastructure companies is being questioned on a systemic level.
Baird Investment Strategy Analyst Ross Mayfield said in an interview with Reuters:
Long-term interest rates exceeding 5% and approaching 6% pose a problem for marginal borrowers. For those below the tier of the four largest cloud service providers, the situation is much more difficult.
In contrast, hyperscale cloud service providers represented by Alphabet, Microsoft, Meta, and Amazon have been relatively resilient during this round of selling off due to their high profitability and sound management, with declines of around 2%.
Argent, the portfolio manager of Asset Management, pointed out that these four companies, together with SpaceX, are responsible for approximately 75% of data center investments in the United States, and their data center investment returns have been quite good.
However, CoreWeave is currently seeking to obtain financing at a lower cost from insurance companies to maintain the infrastructure construction of AI. But analysts point out that with the yield on its unsecured bonds having exceeded 15%, the prospects for finding a cheaper source of funding than its current capital structure are not optimistic.