ASML delivered a third-quarter report that far exceeded expectations, and with overwhelming demand for orders and an active plan to expand production, it effectively countered the market's long-held pessimistic views regarding the decline in lithography intensity.
According to research reports released by JPMorgan Chase and UBS on October 14, ASML's earnings per share in the third quarter exceeded market expectations by more than 20%, and its gross margin significantly surpassed the upper limit of the company's own guidance. More importantly, the company disclosed that the current backlog of orders has already exceeded the existing production capacity limits for 2027 and 2028, and customers have even begun to compete for delivery windows in 2029 and even 2030. The company is considering increasing its production capacity expansion rate in 2028 to over 30% from the previously planned rate.
The aforementioned signals directly undermined the core logic of the bears. JPMorgan Chase pointed out that the median annual revenue growth rate for ASML in 2026 reached 36.2%, which is higher than the bank's forecast of a 31% growth rate for the global wafer fab equipment ( WFE ) market. This indicates that ASML is outperforming the overall equipment market – the historical bear argument of “declining lithography intensity” has been refuted by facts. UBS, on the other hand, expects that driven by rising gross margins and expectations of capacity expansion, the market's consensus earnings per share forecast for 2027 to 2028 will be raised by 5% to 10%.
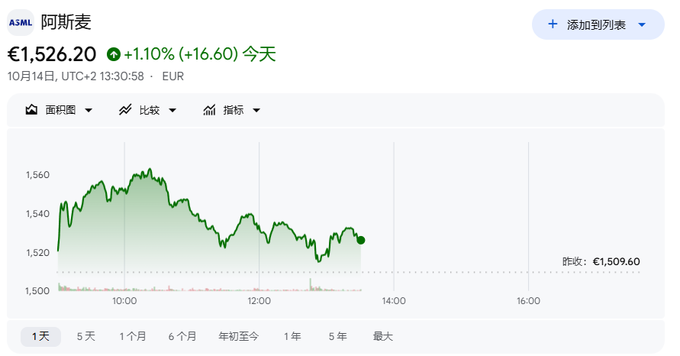
After the financial report was released, ASML's European shares tumbled, only to subsequently experience a V-shaped reversal, with the stock price rising by nearly 3%.
Third-quarter performance far exceeded expectations, with gross margin being the biggest highlight.
ASML Achieved net sales of 11.662 billion euros in the third quarter, which is basically in line with market expectations.
In terms of revenue structure, device sales amounted to 837.3 million euros, which is about 4% to 5% lower than expected; however, revenue from installed basic management ( IBM ) services reached 328.9 million euros, about 13% higher than anticipated, and became an important support for the overall revenue.
The gross margin performance was particularly outstanding. In the third quarter, the gross margin reached 57.5%, which not only exceeded the company's previous guidance range of 55% to 57%, but also surpassed the consensus forecasts of JPMorgan Chase and the market by about 132 to 134 basis points. Driven by this, the operating profit for the third quarter amounted to 5.173 billion euros, with an operating margin of 44.4%, both of which were about 5% higher than market expectations.
In terms of earnings per share, the diluted earnings per share for the third quarter were 12.93 euros, which is 19.2% higher than JPMorgan Chase's forecast and 20.8% higher than the market consensus, representing a significant excess. UBS data also shows that EBIT for the third quarter was about 5% higher than the market consensus.
Guidance for the fourth quarter and the whole year has been significantly raised, exceeding market expectations.
Looking ahead to the fourth quarter, ASML expects its net sales to range from 14.2 billion to 15.2 billion euros, with a median of 14.7 billion euros, which is about 5% higher than the market's consensus forecast.
The gross profit margin for the fourth quarter is expected to be around 57%, which is higher than the market's forecast of 56.4% to 56.7%. According to JPMorgan Chase' calculations, the implied operating profit for the fourth quarter is about 6.779 billion euros, which is approximately 9% higher than the market's consensus forecast.
On an annual basis, ASML has raised its revenue forecast for 2026 from the previous range of 43 to 45 billion euros to 44 to 45 billion euros, with a median of 44.5 billion euros, corresponding to a year-on-year growth rate of about 36.2%. The gross margin for the whole year is expected to be around 56%. JPMorgan Chase estimates that based on the new forecast, the market's consensus expectation for fourth-quarter operating profit will increase by nearly 10%, and the upward revision of the annual earnings per share consensus forecast will exceed mid-teens percentage points.
Order backlogs exceed production capacity limits, and expansion plans are being accelerated
The most market-shocking information regarding this quarter's performance comes from the latest statement by ASML regarding order status. The company disclosed that the volume of orders received in the past quarter has exceeded the upper limit that its current production capacity for 2027 and 2028 can handle, and the demand from customers has extended into 2029 and even 2030.
ASML clearly states that the previously planned low-capacity NA EUV and submerged DUV capacity expansion plans for 2027 and 2028 will not be sufficient to meet customer demands. The company is studying further measures to expand capacity, with a focus on 2028, where the expansion rate is expected to exceed the previously planned 30% growth (with a 30% growth already planned for 2027). In addition, the company is also developing upgrade solutions for the installed equipment to further unleash the potential of existing capacity.
JPMorgan Chase believes that the aforementioned signals have a positive impact on the entire semiconductor equipment sector. Customers are rushing to secure orders for the period from 2029 to 2030, indicating that the sustainability of the industry's upward cycle far exceeds previous expectations.
The core logic of short selling has been disproven, but institutions still maintain high target prices.
The performance of ASML directly responds to a core bearish argument that has long existed in the market: namely, as semiconductor manufacturing processes evolve, the usage intensity of lithography equipment will tend to decline, and the growth rate of ASML will fall behind the overall WFE market.
JPMorgan Chase clearly stated that the median revenue growth rate of ASML of 36.2% in 2026 is higher than the bank's forecast for the market growth rate of WFE at 31%. This proves that ASML is achieving growth that surpasses the market, and this surpassing occurs in the first year of an upward cycle – during which ASML typically takes longer to fully utilize its production capacity due to longer delivery cycles. The bank maintains its overweight rating on ASML, with a target price of 2100 euros, corresponding to an expected price-earnings ratio of about 29.6 times for 2028.
UBS also maintains a “strong buy” rating on ASML, with a target price of 2,350 euros, and expects a return on equity of about 56% over the next 12 months. The bank predicts that as the scale of capacity expansion becomes clearer, there is room for further upward revisions in market forecasts for EUV shipments from 2027 to 2028. Coupled with ongoing improvements in gross margin, this will jointly drive an upward revision in earnings per share valuations.
~~~~~~~~~~~~~~~~~~~~~~~
The above wonderful content is from the Chasing Wind Trading Platform.
For more detailed interpretations, including real-time analysis and frontline research, please join [Chasing the Wind Trading Desk ▪ Annual Membership].