TipRanks writes that although Eli Lilly (Eli Lilly)'s stock is clearly not one of the best-performing stocks this year, its performance is still considered solid compared to cyclical sectors such as finance, which are affected by fluctuations in energy prices and related economic uncertainties.
The author indicates that if cyclical stocks experience a rebound, Eli Lilly is expected to perform relatively poorly compared to cyclical stocks in the short term. Nevertheless, if the risk of economic downturn becomes a reality, and/or if investors' enthusiasm for the prospects of AI company fades, Eli Lilly's strong stock performance could continue until 2027.
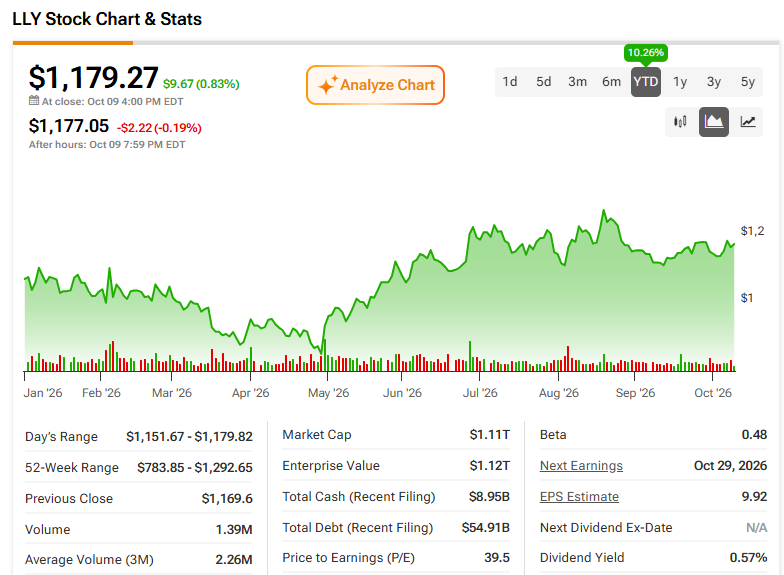
Achieve revenue growth through etiquette
Lilly reported revenue of $23 billion in the second quarter of 2026, a year-on-year increase of 48%. This was mainly driven by strong demand for weight loss drugs Mounjaro and Zepbound, with sales for both increasing by 91% and 46%, respectively.
An obvious downside is that this growth is highly concentrated. The author states that the revenue from these two drugs now accounts for nearly 65% of Eli Lilly's total sales, exposing the company to risks stemming from changes in the demand for weight-loss medications. The author believes that this concentration of revenue supports a more neutral rating for Eli Lilly.
Even with this point to note, Eli Lilly's future prospects remain bright. Analysts expect Eli Lilly to report revenue of $22.3 billion for the third quarter of 2026 when it releases its financial results on October 29, 2026. This will represent a healthy growth of 27% compared to the same period last year.
The author concludes that Eli Lilly remains attractive to large-cap growth investors who wish to diversify their exposure to the AI theme. Moreover, the non-cyclical nature of healthcare revenue typically allows companies to perform better during more challenging economic periods, a point that will be further discussed in the next section.
Will cyclical stocks outperform Eli Lilly in the 2027 period?
Eli Lilly is the largest holding in the healthcare sector SPDR funds ( Health Care Select Sector SPDR Fund , XLV ). The performance of these funds in 2026 was slightly inferior to that of the S&P 500 index. Nevertheless, the healthcare sector still outperformed some cyclical sectors, especially the financial sector; the latter struggled amidst fluctuations in energy prices and economic uncertainty.
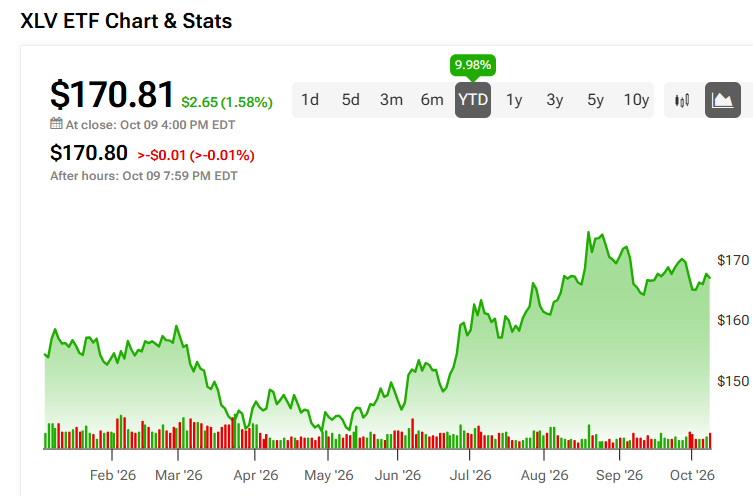
This presents investors with an interesting trade-off. Stocks in the healthcare sector, such as Eli Lilly, benefit from relatively stable demand during uncertain times; however, if economic conditions improve, cyclical sectors may offer greater upside potential. In such a scenario, investors might increasingly favor those stocks that lagged behind in 2026, which could limit Eli Lilly's relative performance.
Based on this, the author believes that there is an opportunity for Eli Lilly to realize some profits before the potential rotation of capital towards cyclical stocks. Although its defensive attributes remain attractive, the possibility of stronger returns in other areas reinforces the author's 'hold' rating for Eli Lilly as we move towards 2027.
Lilly's valuation
The author believes that Eli Lilly's relatively high price-earnings ratio (P/E) multiple in 2026 indicates that its short-term earnings momentum has been largely factored into the market price. At the same time, this high valuation naturally reflects the market's expectation that it will continue to maintain growth momentum in 2027 and beyond. For example, analysts expect Eli Lilly's earnings per share in 2027 to increase to approximately $47.64, corresponding to a profit growth of about 31%.
Based on the price-earnings ratio multiple for 2026 and the expected earnings growth, one can calculate Eli Lilly's PEG ratio, which is the price-earnings ratio divided by the expected earnings growth. The author states that the lower the PEG ratio, generally the better. Eli Lilly's PEG ratio is 1.05, which is considered quite attractive for a large-cap company. For comparison, the author calculated that the PEG ratio for the S&P 500 index is about 1.2.
How Wall Street Views Eli Lilly
On Wall Street, Eli Lilly has received a consistent “strong buy” rating from the market, based on 20 “buy” recommendations, 2 “hold” recommendations, and 1 “sell” recommendation in the past three months. Eli Lilly’s current average target price is $1366.05, which indicates that there is approximately 16% upside potential over the next 12 months.
Conclusion
Looking ahead to 2027, the author believes that this presents an opportunity for defensive companies like Eli Lilly to achieve a profitable conclusion. In fact, although weight loss drugs such as Mounjaro and Zepbound have driven sales growth for Eli Lilly, the high concentration of revenue also poses risks to the company.
Coupled with a relatively high price-earnings ratio of 32.3 times in 2026, the author believes this supports a "hold" rating for Eli Lilly. Of course, this view is clearly more cautious than the consistent "strong buy" rating from Wall Street.
The author indicates that Eli Lilly's growth is far from over, and the attractive PEG ratio of 1.05 is proof of this. However, the author believes that current market dynamics support a tactical shift of some positions from the healthcare sector. Nevertheless, if downside economic risks emerge and/or investors become increasingly skeptical about the prospects of AI companies, Eli Lilly's strong performance could continue.