Marvell Technology ( MRVL ) has become one of the most highly regarded AI concept stocks – it can also be said to be one of the hardest stocks to value.
The company is further delving into the fields of custom chips and high-speed connections, and with the expansion of the AI data center, both of these businesses are expected to benefit. Management currently believes that by the fiscal year 2031, the company's annual revenue is expected to reach between $70 billion and $90 billion, with adjusted earnings per share exceeding $30. The issue is that the price investors are willing to pay for this is not low. Calculated at a valuation of approximately 38 times the expected profits for the fiscal year 2028, MRVL still needs many things to go according to plan.
I don't think the volatility of this stock will become more stable. However, I believe that the improved profit prospects still leave room for this stock to rise in the long term. This is also the reason why I have given MRVL a "buy" rating.
Marvell This 200% increase isn't stable at all.
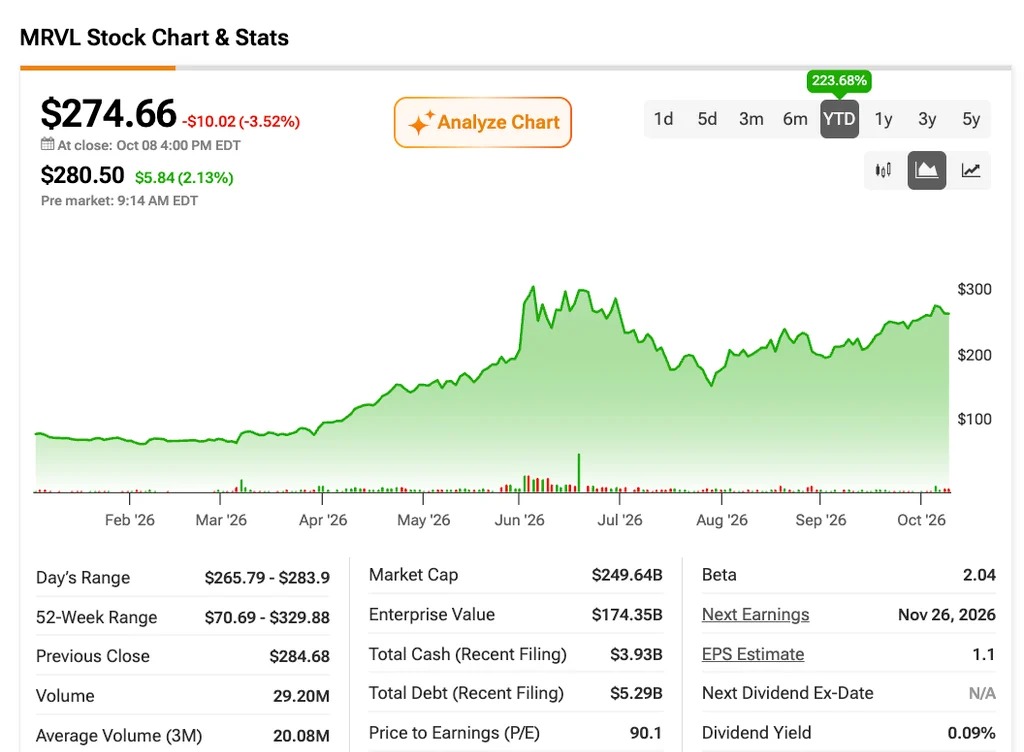
Marvell's initial major driving force came from its continuously expanding exposure in the AI infrastructure sector. In March, NVIDIA ( NVDA ) announced a strategic partnership with the company and invested $2 billion, strengthening Marvell's position in the fields of custom chips and connectivity. In June, Marvell was included in the S&P 500 index, which brought another wave of boost to MRVL.
However, the correction in July also revealed how high market expectations had become. Doubts about the sustainability of large-scale AI expenditures triggered a sharp sell-off in that sector.
However, since then, the fundamentals have improved. Marvell has expanded its cooperation with Google (GOOGL), and in the second quarter of fiscal year 2027, its data center business grew by 46%. The company also raised its revenue forecast for fiscal year 2028 from $18 billion to $20 billion. Looking further ahead, management expects revenue to reach up to $90 billion by fiscal year 2031, which is nearly 11 times the $8.2 billion reported in fiscal year 2026.
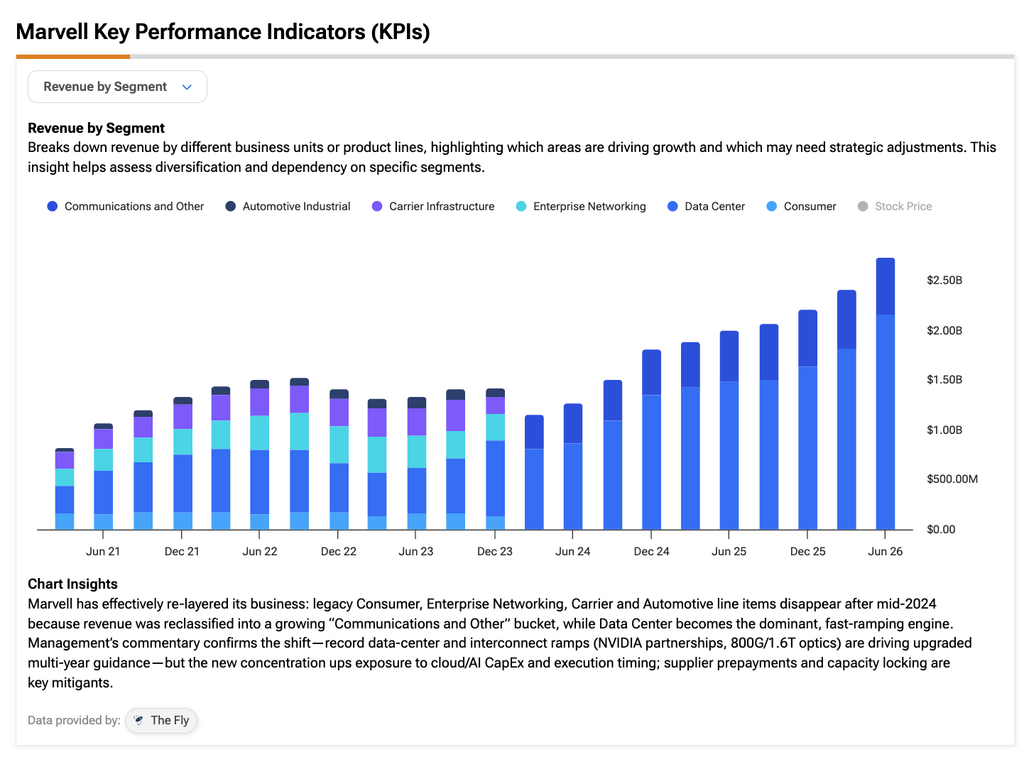
The key point is that the bullish logic is once again gathering momentum. However, after such a substantial increase, how much of these growth expectations has already been factored into the stock price?
Why did MRVL almost halve its market value in July?
If the current question is whether MRVL can continue to rise or will once again face the risk of a 50% drop, then it is necessary to take a closer look at what exactly happened in July.
By mid-June, the stock price of Marvell was around $310 per share. Based on the available forecast data at that time, its valuation was approximately 82 times the expected profits for the fiscal year 2027 and nearly 57 times the expected profits for the fiscal year 2028. Even for a company with rapid growth like Marvell, such a valuation requirement is quite high. In its most recent reported quarter, which was the first quarter of fiscal year 2027, revenue grew by 28%. However, revenue and adjusted earnings per share were only about 1% higher than Wall Street's expectations.
At the same time, AI stocks are also facing heavy selling pressure. Investors are beginning to question whether large cloud providers can continue to sustain such substantial AI expenditures when returns are not yet clear. In fact, Erste Group has downgraded its rating of MRVL from "Buy" to "Hold" due to high valuations and uncertainties in profit margin growth, with part of the reason being the issue of customer concentration.
I believe that this clearly indicates that even with strong fundamentals, if investors are no longer willing to pay a high premium for future growth, MRVL may not be able to avoid another significant correction.
The growth prospects of Marvell make the current valuation seem more reasonable.
At the investor event in October, Marvell raised its revenue forecast for the fiscal year 2028 from $18 billion to $20 billion, driven mainly by its optical interconnection and switching business. Management also stated that by the fiscal year 2031, the company's annual revenue is expected to reach $70 billion to $90 billion, with adjusted earnings per share exceeding $30.
If these goals are achieved, then based on a stock price of $275, the valuation of MRVL would be approximately 9.2 times the expected profits for the fiscal year 2031. Even with a price-earnings ratio of only 15 times, the corresponding stock price would reach $450, which still represents a potential increase of about 64% from the current level.
In my opinion, these constantly changing expectations help to explain why the stock price of Marvell has fluctuated so dramatically: it doubled in just a few months, only to then fall by nearly half. However, to achieve the aforementioned upside potential, continuous spending by large cloud providers, successful volume growth of their products, and strong execution over several consecutive years are all indispensable conditions. Even after the prospects improve, buying at a valuation of nearly 38 times the expected profits for the fiscal year 2028 still leaves little room for error.
According to Wall Street analysts, is MRVL worth buying?
Wall Street analysts are still very optimistic about Marvell overall, giving the stock a unanimous rating of 'strong buy'. Among the 30 ratings issued in the past three months, 26 are 'buy', and only 4 are 'hold'. The average target price for Marvell is $354.56, which means there is still about a 29% upside potential from the current level.
The long-term upside potential of Marvell is worth taking the risk for.
Going long on MRVL at the current price level, from a valuation perspective, the risk may be lower than in mid-June, but this still means having to accept the possibility of significant fluctuations in the stock price.
That being said, I believe that this configuration is still attractive for investors who are willing to look ahead to the next few quarters. Especially with the updated performance guidance – with adjusted earnings per share expected to exceed $30 by the fiscal year 2031 – the bullish case is now more substantively supported than it was earlier this year.
Of course, there is almost no room for error at the execution level, and I also cannot rule out the possibility of another sharp correction during the process. However, if Marvell ultimately comes close to the long-term goals set by management, then in retrospect, today's valuation may prove to be quite reasonable.
Overall, I still tend to be bullish on MRVL, as I believe that the improvement in its long-term profitability makes the risk of another significant pullback worth taking.
Disclaimer and Disclosure: Reporting Issues
Marvell Technology News MORE