After the AI sector drove the chip stocks to continue strengthening this year, Wall Street is still raising its expectations for some companies. Foreign media, comparing Micron with AMD, two popular AI chip stocks, believe that if one only looks at the gap between analysts' target prices and current stock prices, Micron has more room for upward movement in the future.
Micron awaits the release of its quarterly report
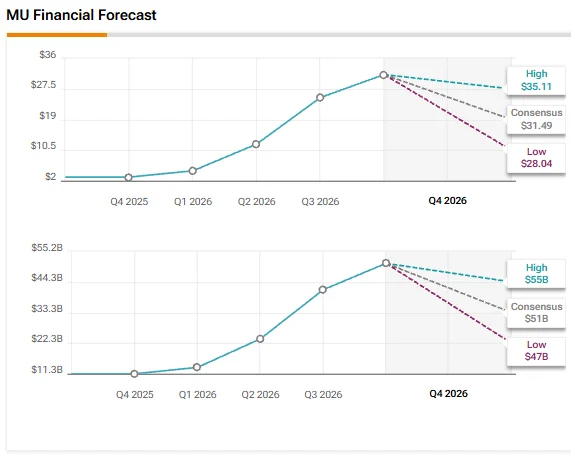
Micron's stock price has risen significantly this year, and market attention has shifted to the fourth quarter results for the fiscal year 2026, which were announced on September 30. The article states that investors are not only focusing on the performance of that quarter but also awaiting the company's guidance for the fiscal year 2027.
Deutsche Bank analyst Melissa Weathers maintains a buy rating on Micron. She believes that demand for DRAM and NAND in the AI scenario remains strong, and the industry's fundamentals may remain so for a longer period. According to her calculations, the tight supply and demand in the DRAM market may intensify further in 2027 and 2028.
She also expects that by 2030, the annual average growth rate of demand for DRAM will be around 21%, which is higher than the historical median level. Although the growth rate of wafer supply is also being raised, it remains lower than the growth rate of demand. Stifel analyst Brian Chin also maintains a buy rating and expects Micron's performance in the fourth fiscal quarter to still exceed market expectations, although the extent of exceeding expectations may be smaller than in the previous quarters.
- Wall Street's rating distribution for Micron is 29 buys and 1 hold.
- Average target price is $1,564.44.
- The upside potential corresponding to the current stock price is approximately 43%.
AMD Reaches a New Level in Market Value
In terms of AMD, the article mentions that the company's market value reached $1 trillion for the first time on September 21. Market sentiment was supported by server CPU and AI GPU demand expectations. The early progress of Muse AI and agent under Meta was also seen as positive. Additionally, AMD's position in the computational power demand related to intelligent agents AI was also noted.
AMD The stock price has increased by more than 190% within the year. In the second quarter of 2026, the company's revenue grew by 50% year-on-year, reaching $11.54 billion, with data center business revenue increasing by 107% year-on-year. This is also an important reason why Wall Street continues to be bullish on this stock.
Institutions remain bullish, but the room for growth is limited.
Truist Analyst William Stein recently reiterated the buy rating on AMD, stating that management remains confident about demand momentum and execution. Although the company expects gross margin to face temporary pressure in the fourth quarter of 2026, customer demand for AI servers and CPU servers remains strong, and the supply chain is generally able to meet delivery commitments.
However, he slightly lowered his forecasts for AMD's gross margin and earnings per share for the fourth quarter, but maintained the same expectations for earnings per share in 2027. The article states that Wall Street's overall rating for AMD is still positive, but looking at the average target price, the room for further increase has clearly narrowed.
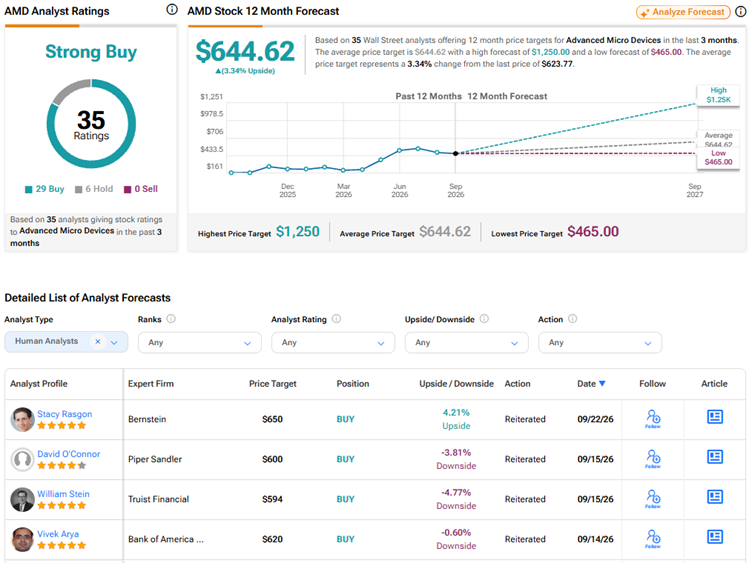
- Wall Street's rating distribution for AMD is 29 buys and 6 holds.
- Average target price is $644.62.
- The upside potential corresponding to the current stock price is approximately 3.3%.
After comprehensive analysis of various articles, Wall Street has not shifted to a bearish stance AMD. Instead, when it comes to two AI chip stocks, there is a greater inclination to believe that the current valuation of Micron is even more disconnected from its target price. Moving forward, Micron's upcoming quarterly report and new fiscal year outlook will serve as direct benchmarks for the market to test this judgment.