

Apple reported revenue of $114.5 billion in the fourth quarter of fiscal year 2026, a year-on-year increase of 12%, exceeding analysts' expectations.
iPhone reported a 17% increase in revenue to $57.58 billion, while Mac saw a 24% rise in sales.
However, the lower gross margin forecast for the December quarter and the continuously rising memory costs remain the main concerns for AAPL investors.
Apple once again delivered quarterly results that exceeded expectations, but its outlook presents a more complex picture for investors. Strong demand for iPhone and higher sales of Mac supported revenue growth, and the Services business also continued to set record sales. However, rising memory costs and weaker forecasts for gross margin during the holiday quarter have raised doubts about Apple's profitability. As investors look beyond the latest results, the focus is shifting to whether the company's growth momentum will be sufficient to support another rise in stock prices.
Apple's Q4 performance exceeded expectations due to strong sales of iPhone.
iPhone remains the largest source of revenue, with a 17% increase to $57.58 billion. Mac saw a 24% increase in revenue to $10.79 billion; Services reported revenue of $31.57 billion, a year-on-year increase of 10%. However, not all business lines achieved growth. iPad experienced a 10% decline in revenue to $6.23 billion; Wearables, Home, and, and Accessories all saw an 8% decline in revenue to $8.3 billion. Revenue in the Greater China region increased by 21% to $17.54 billion, but this was below analysts' expectations.
Overall, these results indicate that Apple's core product business remains strong, however, the weaker performance in some categories is still a concern.
Rising memory costs threaten Apple's profit margins
Despite exceeding expectations in performance, Apple's guidance for the December quarter still raises concerns about profitability. The company expects the gross margin to be between 45% and 46%, while Q4 is at 47.9%. Management stated that a significant portion of the expected pressure comes from rising memory costs, which are driving up expenses in the hardware business.
Apple also expects that the revenue growth rate for the December quarter Services will be between 8% and 9%, lower than Q4's 10%. At the same time, the company expects the overall revenue growth rate for the holiday quarter to be between 7% and 10%. This guidance indicates that demand remains strong, but higher component costs may limit the benefits brought by additional sales. For investors, the key question is whether Apple will be able to maintain its profit margin while continuing to grow revenue.
Apple Stock Price Outlook: Can AAPL Regain Its Upside Momentum?
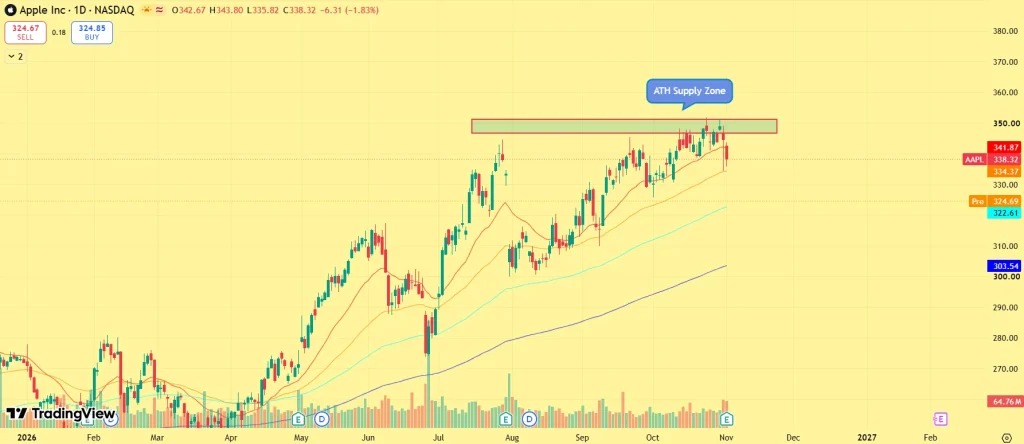
After Apple announced its financial results, the stock price of AAPL came under pressure, indicating that investors are more concerned with forward guidance than whether the quarterly results exceeded expectations themselves. During the pre-market trading session, the stock price of AAPL fell by over 4%. However, whether the stock price can regain upward momentum remains important. If it continues to stay above the direct resistance level of $340, it may enhance the expectation for a rebound and open up space for further gains towards $350.
At the same time, ongoing selling pressure may push the stock price down to the support level around $320, followed by $316, and continue the pullback after the earnings report. The stock needs stronger buying interest to confirm that investors have digestied their concerns about rising costs and pressured profit margins.
The next step of the trend is likely to depend on how the market assesses Apple's expectations for holiday quarter performance, as well as the company's ability to manage memory expenditures.