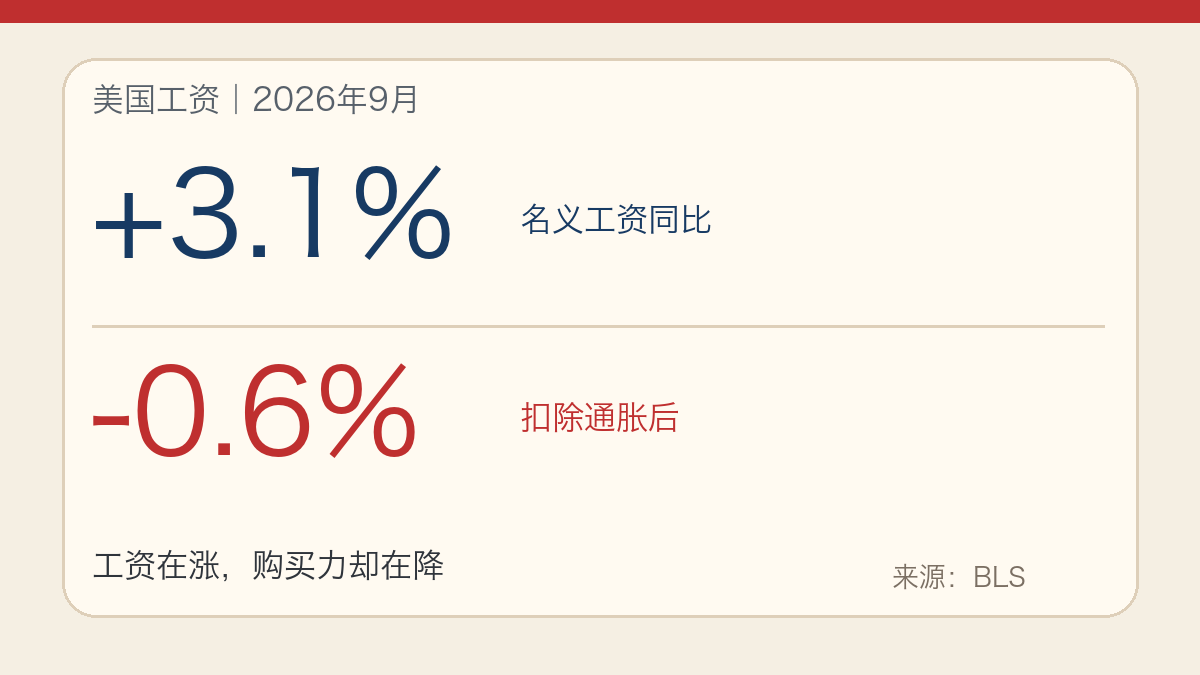


U.S. employers continued to experience rising labor costs in the third quarter, but when these wage figures are adjusted for real purchasing power, the trend is the opposite. According to data released by the U.S. Bureau of Labor Statistics on October 30th, over the three months ending in September, the total compensation for private sector workers increased by 0.8% after seasonal adjustments; over the past 12 months, it rose by 3.4%. Wages and salaries saw a year-on-year increase of 3.1%, but when calculated in constant dollars, they actually decreased by 0.6%.
In the same set of data, it is possible for "employers paying more" and "workers' actual wages decreasing" to both be true at the same time. The former records the nominal compensation cost, while the latter takes into account changes in prices. Referring only to a 3.1% wage increase ignores the erosion of purchasing power caused by inflation; focusing solely on the decline in actual wages also overlooks the fact that companies' labor expenses are still rising.
Welfare costs are outpacing salaries.
Total compensation in the third quarter increased by 0.8% month-on-month, with wages and salaries rising by 0.7% and welfare costs increasing by 0.9%. Over a one-year period, the welfare costs for private sector workers increased by 3.9%, which is higher than the 3.1% increase in wages and salaries. This indicates that the employment pressure on companies comes not only from salary bills; medical expenses, insurance, and other benefits are also contributing to rising costs.
The year-on-year increase in health benefits reached 6.4%, which is the most prominent item in the table. The wage changes experienced by employees do not necessarily coincide with the total cost per employee as seen by employers. Enterprises may face higher total compensation expenses, but employees may not see a corresponding increase in their take-home income.
This also represents the difference between the Employment Cost Index and the average hourly wage. This index uses a fixed employment weight to reduce the interference of changes in industry and job composition on the readings. If the proportion of high-paying jobs suddenly increases, the simple average wage may be inflated by structural changes; the fixed-weight index is more closely aligned with the actual changes in the costs of similar jobs. What it reflects is how labor prices change, not how much money a particular family has earned more this month.
Quarterly comparisons also indicate a cooling trend. The total compensation for private sector workers has slowed from 0.9% over the three months to June to 0.8%, with both wage growth and benefits growth remaining at 0.8%. There has been no acceleration in either wage or benefits growth; across all workers, wage growth has decreased from 0.9% to 0.7% on a quarterly basis. This is more indicative of a marginal slowdown in cost growth rather than a sudden decline in labor costs.
The gap between unionized and non-unionized positions is reflected in the salary structure.
In the past 12 months, the total compensation of workers affiliated with civil unions increased by 4.3%, while that of non-union workers rose by 3.3%. For wages and salaries, union workers also saw an increase of 4.3%, compared to 3.0% for non-union workers. Welfare costs, on the other hand, increased by 4.3% and 3.9% respectively.
These numbers cannot directly prove that union membership is responsible for all the differences. Industry, position, region, and contract duration also affect the results. However, they do at least indicate that labor costs do not follow a uniform pattern. Depending on the industry in which a company operates and the way its employees are organized, the pressures regarding wages and benefits felt by those companies will vary.
The paths for workers in state and local governments differ again. In the third quarter, total compensation increased by 0.6% month-on-month, with wages and salaries rising by 0.6% and benefits increasing by 0.7%; over the past year, total compensation has risen by 3.5%. However, wages and salaries in constant dollars decreased by 0.5% year-on-year, which is in line with the weakening trend of actual wages for private sector workers.
The weights will be changed in the next reading as well.
This September data also includes a note regarding methodological changes. The Bureau of Labor Statistics indicates that starting with the data for December 2026, the Employment Cost Index will update its fixed employment weights and remove compensation costs for work-related injuries. The next report will be released on January 29, 2027.
Weight updates will not render the current data invalid, but they will change how the index represents the job structure in the United States in the future. The distribution of industries and occupations will change, and if the old weights are used for a long time, the gap between the index and the actual employment composition will widen. When analyzing changes over time, it is necessary to separate the methodological adjustments from economic changes.
The core contradiction in September is not complicated: nominal labor costs continue to rise, benefits are increasing faster than wages, yet inflation-adjusted wages are declining. For employers, this is a cost structure issue; for workers, it's a matter of purchasing power; for policy observers, it's a clue as to whether wage pressures will continue to be transmitted to prices. A single figure of 3.4% cannot encompass these three aspects; what truly changes the assessment are the differences between the individual components.