The strong rebound in the healthcare sector is sending an uneasy signal throughout the market.
The healthcare sector has recently risen to become one of the top-performing sectors in the S&P 500. Last week, as concerns about the artificial intelligence bubble continued to rise, the valuation discount of this sector relative to the S&P 500 completely disappeared – the forward price-earnings ratio of the Healthcare Select Industry SPDR ETF ( XLV ) rose to 19.3 times, slightly higher than the overall level of the S&P 500. Just a year ago, this sector still had a 25% valuation discount relative to the S&P 500. On Monday this week, XLV rose by more than 2% in a single day, Moderna soared by 6.7%, and Bristol to Myers Squibb increased by 4.9%.
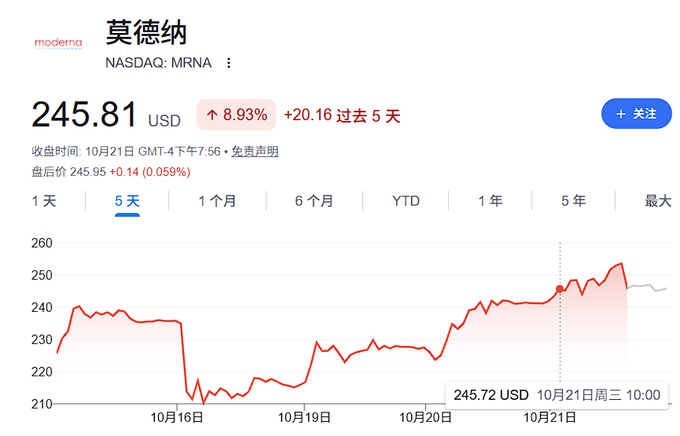
According to a report by The Wall Street Journal on the 21st, the logic behind this round of gains is not complicated: investors are using healthcare stocks to hedge against the risks of the collapse of AI transactions. Concerns that rising interest rates may suppress AI capital spending are driving funds away from highly volatile tech stocks and towards more stable, less cyclical defensive sectors. Historically, the healthcare sector has outperformed the broader market in environments of tightened credit and bursting tech bubbles, and this characteristic is once again attracting market attention.
However, the strengthening of medical stocks is also a warning sign in itself – it indicates that more and more investors are starting to buy "insurance" against potential market downturns.
Valuation discount disappears: a dramatic reversal within a year
The healthcare sector has been in a "discounted range" in the market for several years. The pressure of drug pricing has persisted under both the Biden and Trump administrations, and the soaring medical costs for insurance companies have deterred investors. Coupled with the market style dominated by AI trades, healthcare stocks were largely neglected for a time.
A year ago, the discount of this sector relative to the S&P 500 was as high as 25%. Today, that discount has been eliminated. According to FactSet data, XLV currently has a forward P/E ratio of 19.3 times, which is slightly higher than the overall level of the S&P 500. This is the first time in recent years that the healthcare sector has once again gained a valuation premium.
Goldman Sachs' head of healthcare research in the United States, Asad Haider, pointed out that the healthcare sector can typically maintain a valuation premium when three conditions are met simultaneously: investors maintain confidence in medical innovation, there is concern about the sustainability of profits in other sectors, and policy uncertainties are relatively controllable. He believes that all three of these conditions are currently largely in place.
Historically, it is not common for the healthcare sector to maintain a valuation premium over a prolonged period; such periods were mainly concentrated between 2003 and 2007, as well as from 2013 to 2015. There were also brief instances at the end of 2022 during a surge in inflation and the Federal Reserve's aggressive interest rate hikes, but these lasted for a shorter duration.
The experiences of the mid-2000s represent the most relevant historical parallel at present. Back then, geopolitical conflicts in the Middle East drove up energy prices, while the Federal Reserve continued to raise interest rates; at the same time, the prosperity of the housing market was supporting overall economic profits—highly similar to the current prosperity driven by AI. During that period, the forward price-earnings ratio of the S&P 500 fell from around 18 times in 2004 to about 15 times in 2007, yet the healthcare sector maintained a valuation premium due to its more stable earnings.
The common underlying theme of these two eras is: against the backdrop of continuously rising debt costs, there are deep-seated doubts in the market about whether prosperity can continue to exist.
Fundamental support: Leading companies have clear growth prospects
The regression of valuation premiums is not solely supported by defensive logic; the fundamentals of some leading companies also provide strong endorsement.
Haider indicates that Johnson & Johnson expects to achieve double-digit sales growth by the end of this decade; Eli Lilly, on the other hand, benefits from the strong demand for its diabetes and obesity drugs Mounjaro and Zepbound, with sales expected to grow by more than 30% this year. These two companies together account for approximately 25% of the weight of XLV healthcare ETF, and thus have a significant impact on the overall valuation of the sector.
Policy changes have also provided some support for the healthcare sector. According to The Wall Street Journal, more than a dozen pharmaceutical companies have reached agreements with the Trump administration, sacrificing prices in exchange for tariff exemptions. At the same time, if the Democratic Party wins at least one chamber of Congress in next month's elections, the split government scenario would significantly reduce the likelihood of major new legislation before the 2028 general elections.
However, there is a clear differentiation within the sector. Insurance companies still face a high degree of uncertainty. Mizuho Medical Strategist Jared Holz stated that as the initial selection for 2028 approaches, discussions about "universal healthcare" ( Medicare for All ) may heat up again, which will put pressure on companies such as UnitedHealth Group and Humana. In contrast, the policy environment faced by pharmaceutical manufacturers and medical device suppliers can be said to be the most stable in many years.
However, this “policy” does not come without a cost.
It is reported that the defensive nature of the healthcare sector does not mean zero risk. Investors who entered healthcare stocks at the beginning of 2006 lagged behind the broader market over the following nearly two years. It was not until the financial crisis erupted that the healthcare sector truly demonstrated its resilience to declines—its losses were much smaller than those of the overall market—and it went on to outperform the broader market for a full ten years thereafter. In contrast, industries that led the bull market before it took several years to recover.
The current core issue is: Will AI become the “housing bubble” of this cycle? If the answer is yes, then even if one buys medical stocks at a valuation slightly higher than the market price, it may turn out to be a profitable transaction in hindsight. However, if the prosperity of AI continues, investors who withdraw early to defensive sectors will incur an opportunity cost.
No one can predict when the music of the market will stop. However, the unusual movements in the healthcare sector have clearly signaled to investors that more and more people are quietly preparing for the worst-case scenario.