

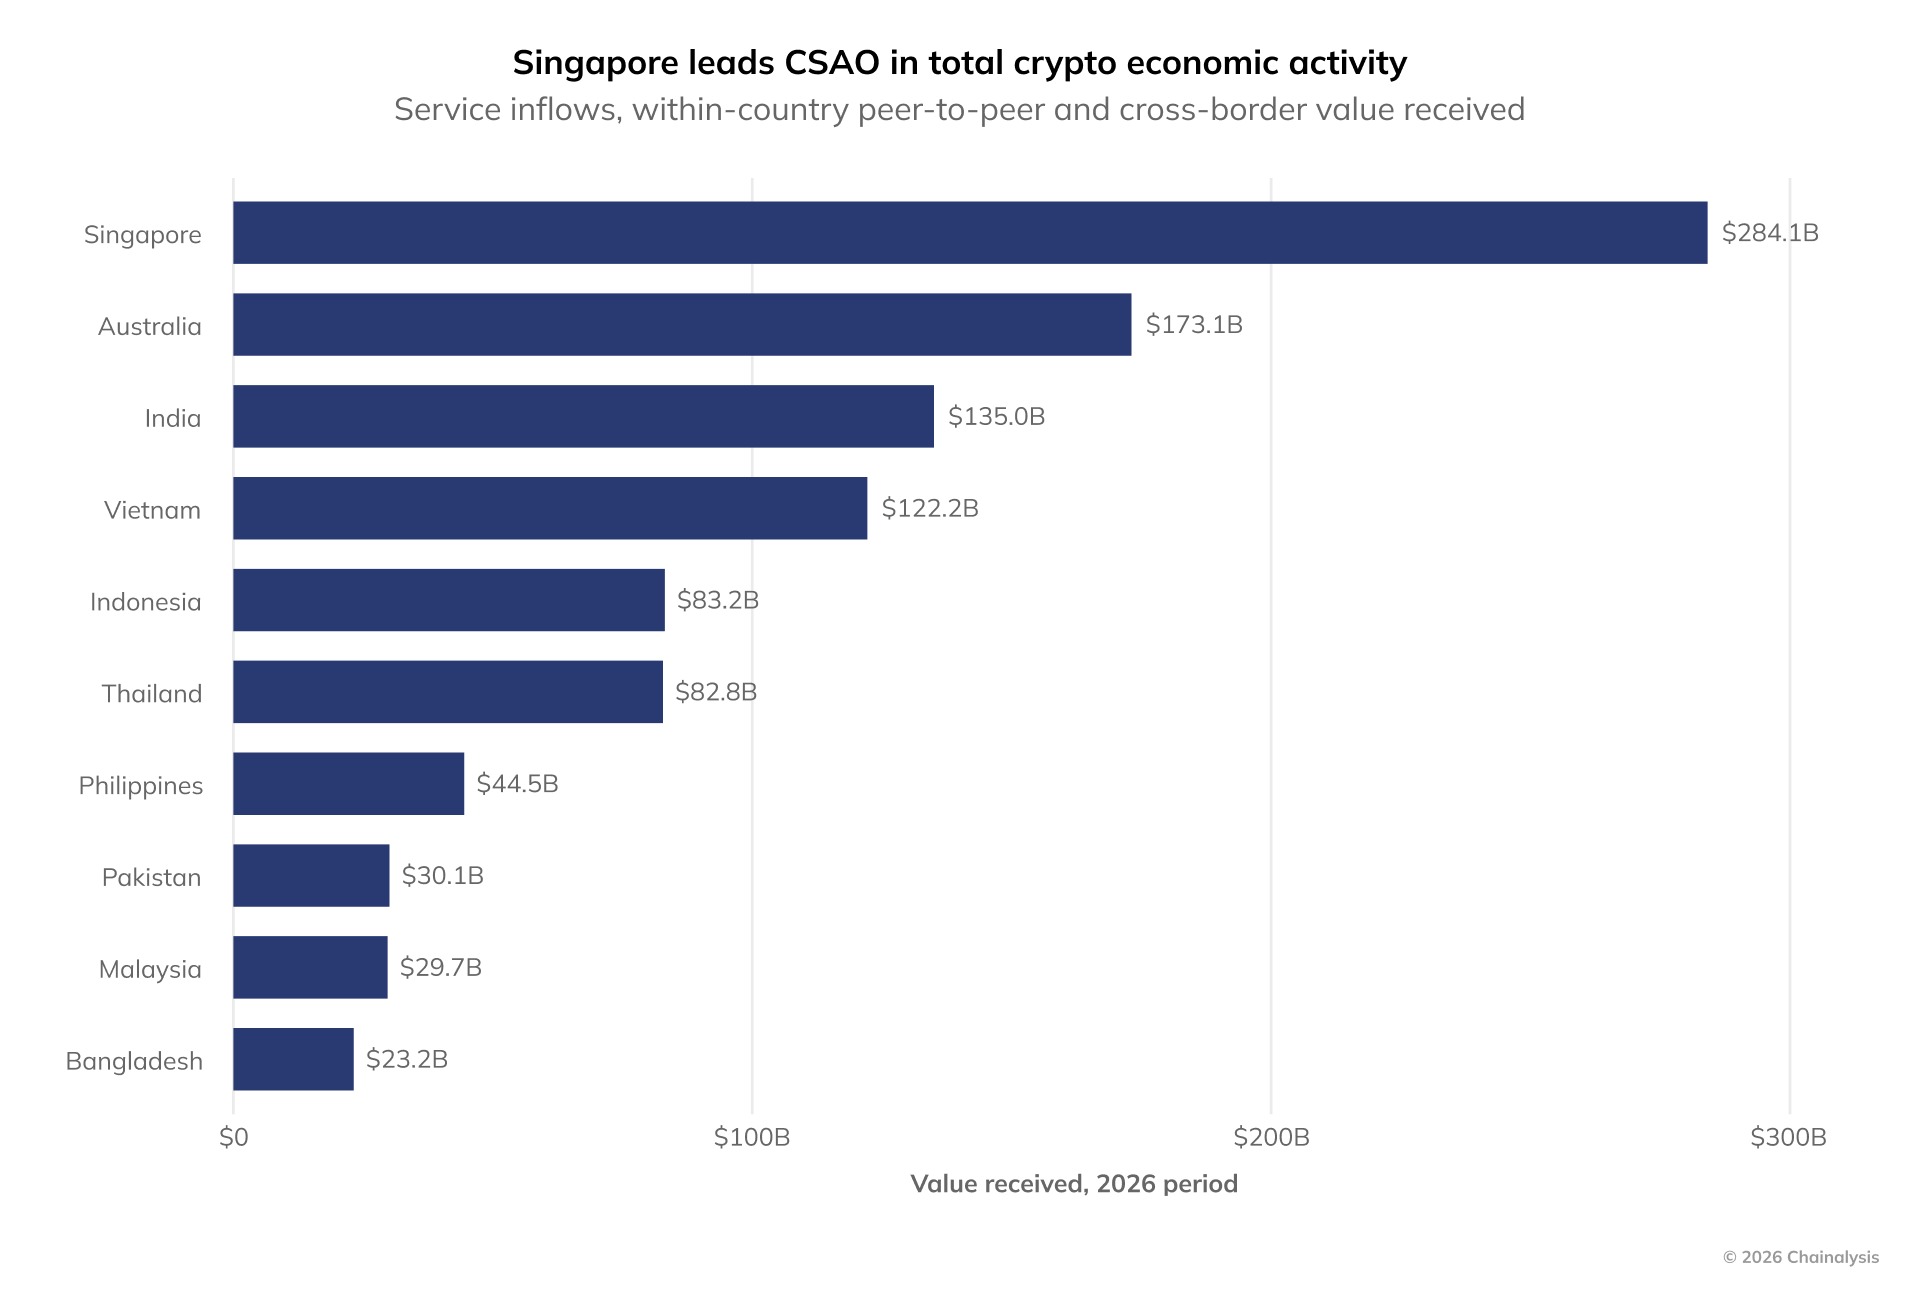
According to Chainalysis data, in the year up to June 2026, Singapore's crypto activities grew by 55.4%, reaching $284 billion, reversing the overall contraction trend in the region and once again becoming the largest crypto economy in the Middle East, Southeast Asia, and Oceania ( CSAO ).
According to Chainalysis, a large portion of this growth came from institutional platform activities, with this segment increasing by 94% to reach $60 billion, and it was mainly concentrated among a few market makers, over-the-counter trading companies, and institutional brokers. Chainalysis indicates that during the same period, the entire CSAO crypto economy contracted by 6.8%.
Chainalysis to Cointelegraph indicates: 'The growth of the ecosystem on the Singaporean institutional platform is very concentrated, mainly reflected in the high trading volume activities of existing platforms, rather than the dynamic entry of new services.'
These findings come at a time when Singapore is tightening regulations on cryptocurrencies while supporting tokenization, stablecoins, and digital asset settlements.
In 2025, MAS requires local crypto companies that provide services to overseas customers to obtain licenses or withdraw from the market. Tianwei Liu, the CEO of StraitsX, stated that this measure has reduced speculative activities and at the same time allowed more institutional participants, including banks and large corporations, to continue using blockchain in production environments.
At the same time, MAS has also expanded its initiatives related to tokenization and settlement. Its BLOOM plan supports pilots that use regulated stablecoins and tokenized bank currencies. On March 25th, Ripple joined this plan to test the use of RLUSD for cross-border trade settlement.
The Philippines, Thailand, and Vietnam are promoting micro-P2P activities.
As the activities of institutions in Singapore stand out, Chainalysis has noticed that the growth of small-scale peer-to-peer (P2P) activities in the Philippines, Thailand, and Vietnam is on the rise.
During the reporting period, these three countries recorded a total of 5.4 million P2P transactions, including both domestic and cross-border transactions. The amount per transaction was less than $10,000, accounting for 14.4% of the global total, yet these three countries only represent 2.5% of the global crypto economy.
In these three markets, more than four-fifths of domestic P2P transfer amounts are less than $1,000, with an average transfer size of $618; in contrast, the average transfer size in other regions of the world is $1,210.
In the Philippines, the International Monetary Fund previously stated that authorities believed the use of cryptocurrencies was mainly driven by remittances and investments. However, data from the World Bank shows that by 2025, personal remittances will account for 8.5% of the country's GDP.
In June, Vietnamese media Tuoi Tre reported that P2P transactions have become an important entry point for fiat currencies, as the Vietnamese dong is not widely supported for direct cryptocurrency transactions. In March, Reuters reported that most Vietnamese cryptocurrency traders rely on overseas exchanges, which has made P2P channels an important means for users to transfer funds between their local bank accounts and the cryptocurrencies traded on these platforms.
In Thailand, the country's Securities and Exchange Commission stated in September that it had observed a significant increase in the volume and value of stablecoin transactions, particularly for USDT.
At the same time, the use of cross-border stablecoins is on the rise. Chainalysis indicates that in each market it analyzed, cross-border stablecoin activity exceeded domestic activity, and the scale of cross-border activity across the region was 3.2 times that of domestic activity.
Thailand and Vietnam each have sizable domestic stablecoin markets, with scales of $10.4 billion and $6.9 billion respectively, while cross-border stablecoin activities are significantly larger than domestic activities.
In the Philippines, PDAX, the CEO and founder of Nichel Gaba, estimates that 5% to 10% of remittances entering the country are settled through stablecoins, and added that major remittance companies are promoting stablecoin settlement programs in the country.
In July, the Philippine Islands Bank disclosed plans to launch a stablecoin settlement pilot, aimed at reducing the costs and shortening the processing time for making overseas payments to freelancers and remote workers in the Philippines.